The Big Story
Quick Take:
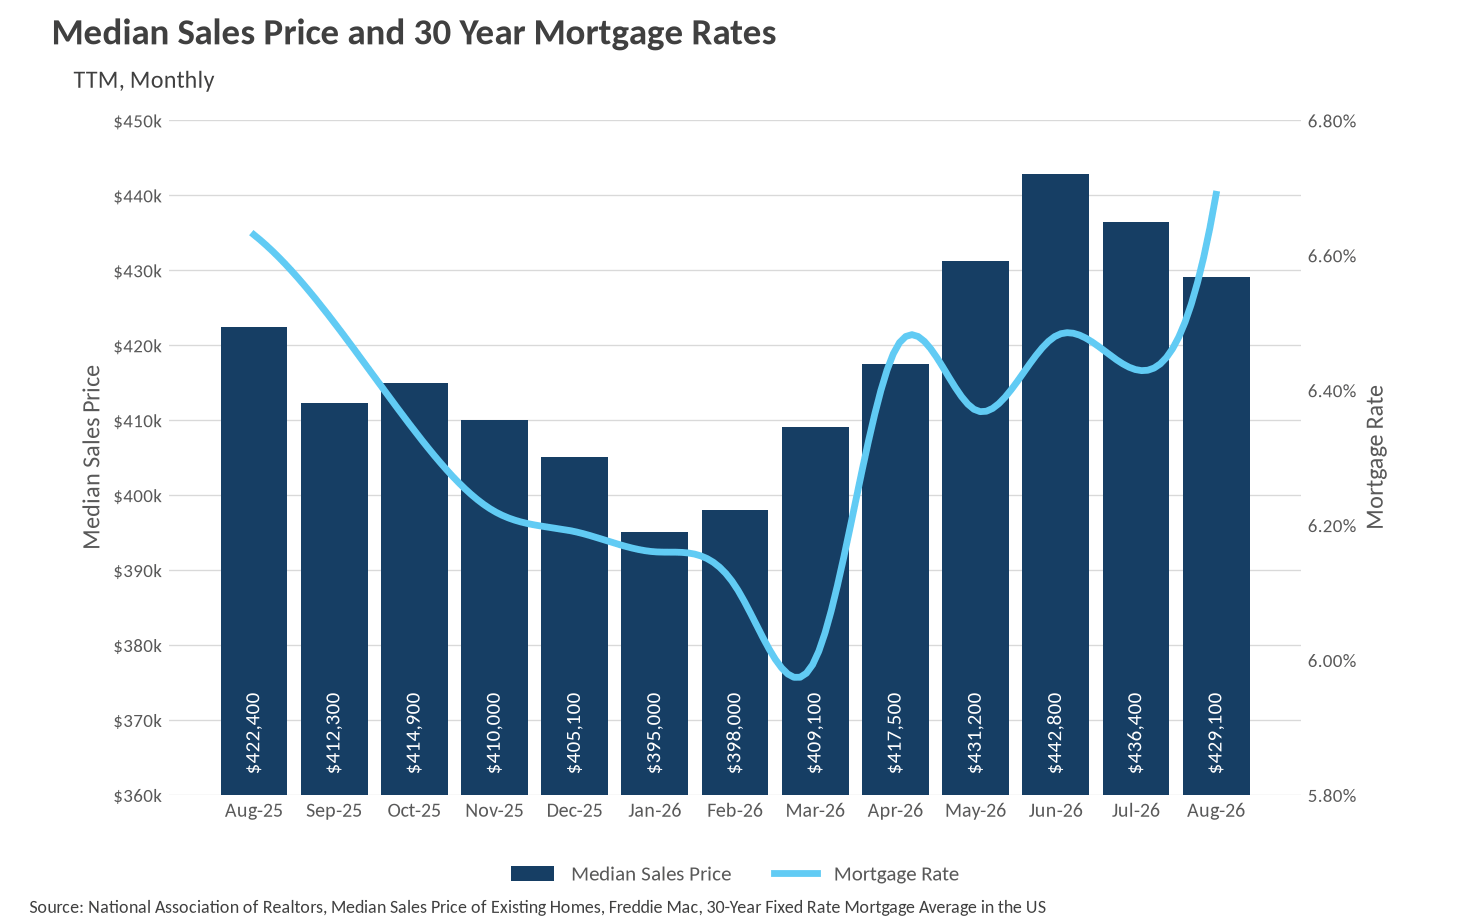
- Median home sale prices slipped for the second straight month in August, falling to $429,100 from June's peak of $442,800, though they remain slightly above where they were a year ago.
- Inventory pushed higher again in August, reaching 1,620,000 homes for sale, the highest level we have seen in this cycle and nearly 6% above last year.
- Existing home sales fell to 3,980,000, the softest reading in over a year, as mortgage rates climbed to 6.69% in August and 6.71% in September.
Note: You can find the charts & graphs for the Big Story at the end of the following section.
*National Association of REALTORS® data is released two months behind, so we estimate the most recent month's data when possible and appropriate.
The spring rally has given way to a summer cooldown
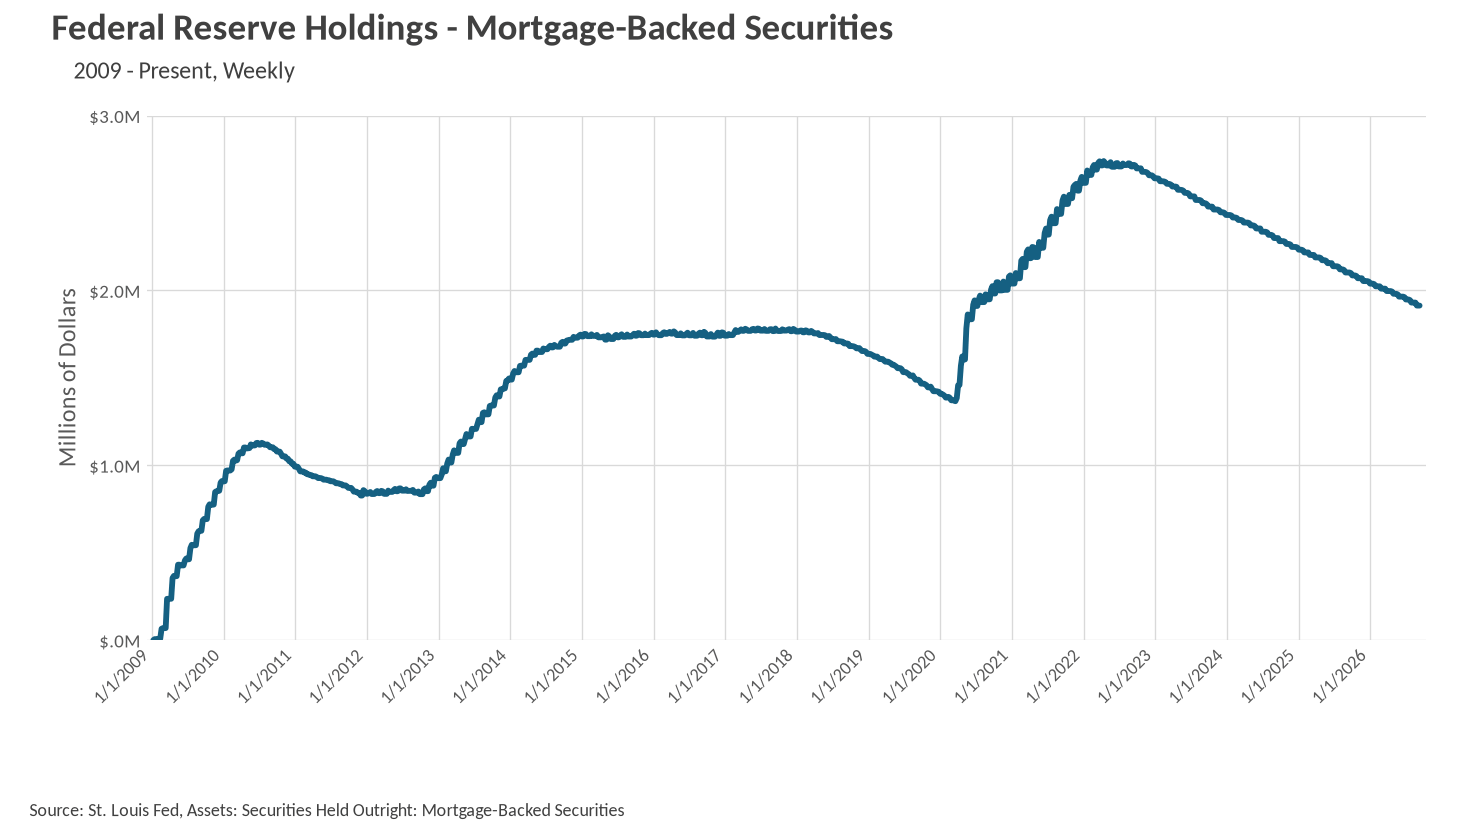
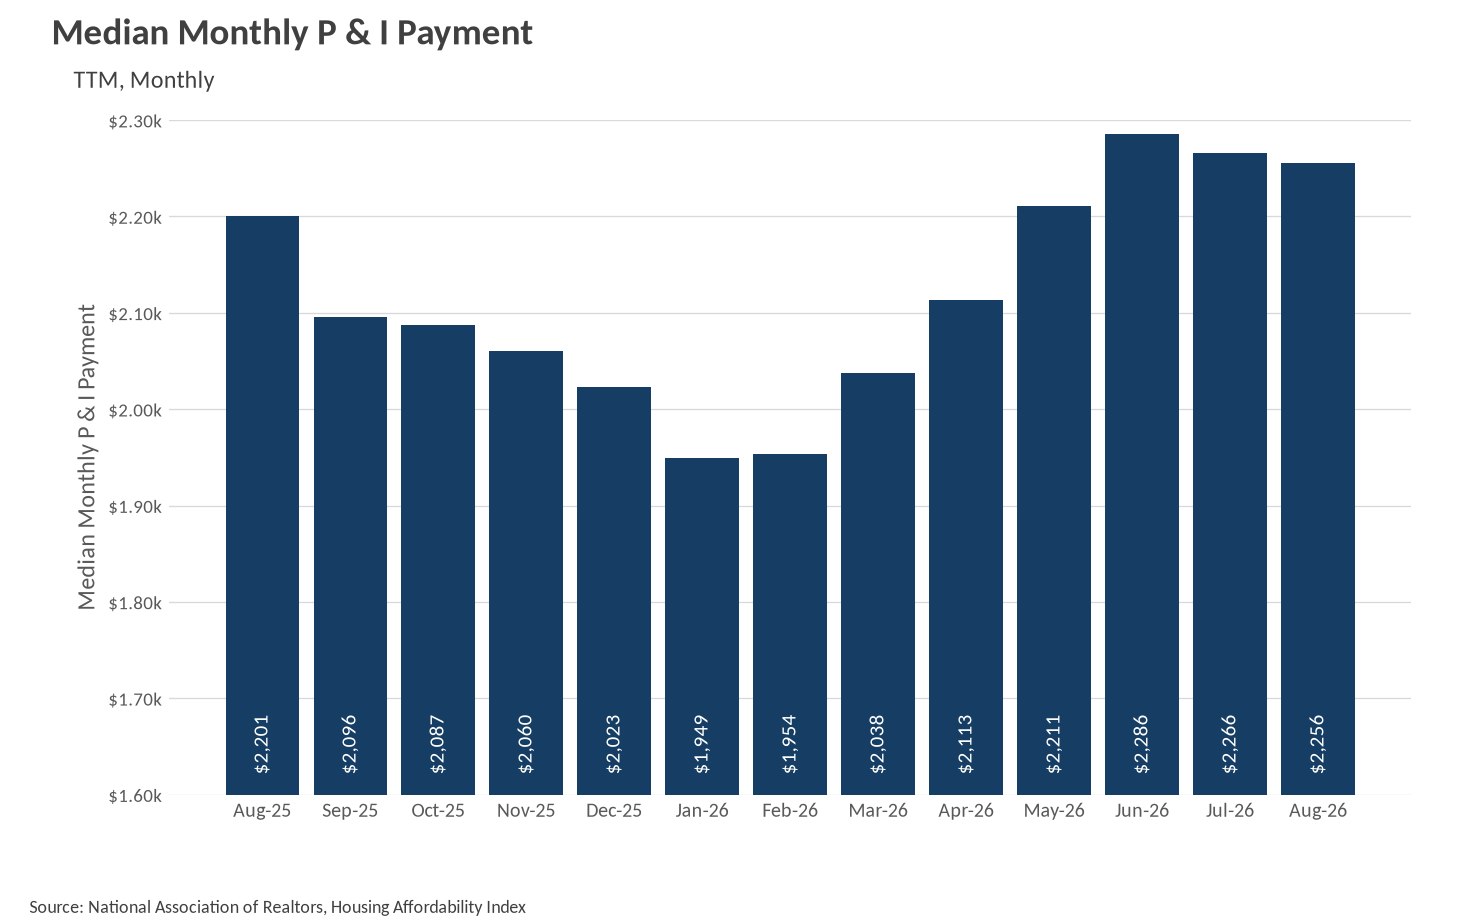
After five straight months of gains carried the median sale price to $442,800 in June, prices have now declined in each of the past two months. In August, the median home sold for $429,100, a 1.67% month-over-month decline from July's $436,400 and a 3.09% pullback from the June peak. The one bright spot is that prices are still running 1.59% above the $422,400 median we saw in August of last year, so the year-over-year comparison remains positive even as the seasonal momentum fades. The affordability story, however, has turned decisively less friendly. Mortgage rates jumped to 6.69% in August and edged up again to 6.71% in September, the highest readings in this entire data series and a full 71 basis points above the 6.00% low we saw back in March. The median monthly principal and interest payment now sits at $2,256, which is 2.50% higher than the $2,201 buyers were paying a year ago and more than $300 above the $1,949 January low. In other words, the affordability cushion that lower rates provided at the start of the year has now been completely erased. It is also worth noting that the Federal Reserve's mortgage-backed securities holdings have continued to run off, declining from roughly $2.05 trillion at the end of last year to about $1.91 trillion in September, which removes a meaningful source of demand for mortgage debt and helps explain why rates have been drifting higher even as the broader market cools.
Inventory keeps building, and that is the real story this month
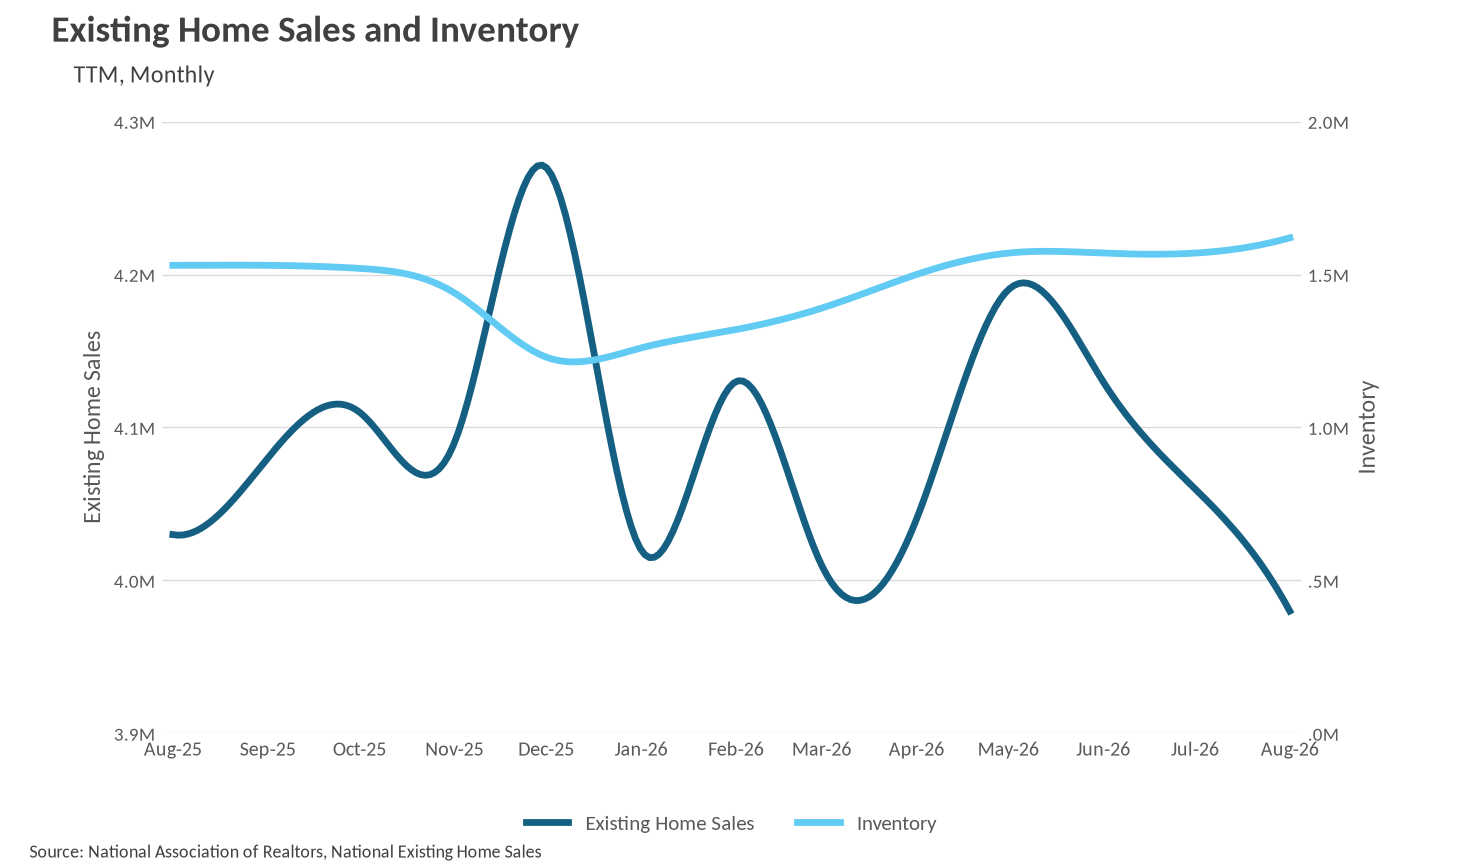
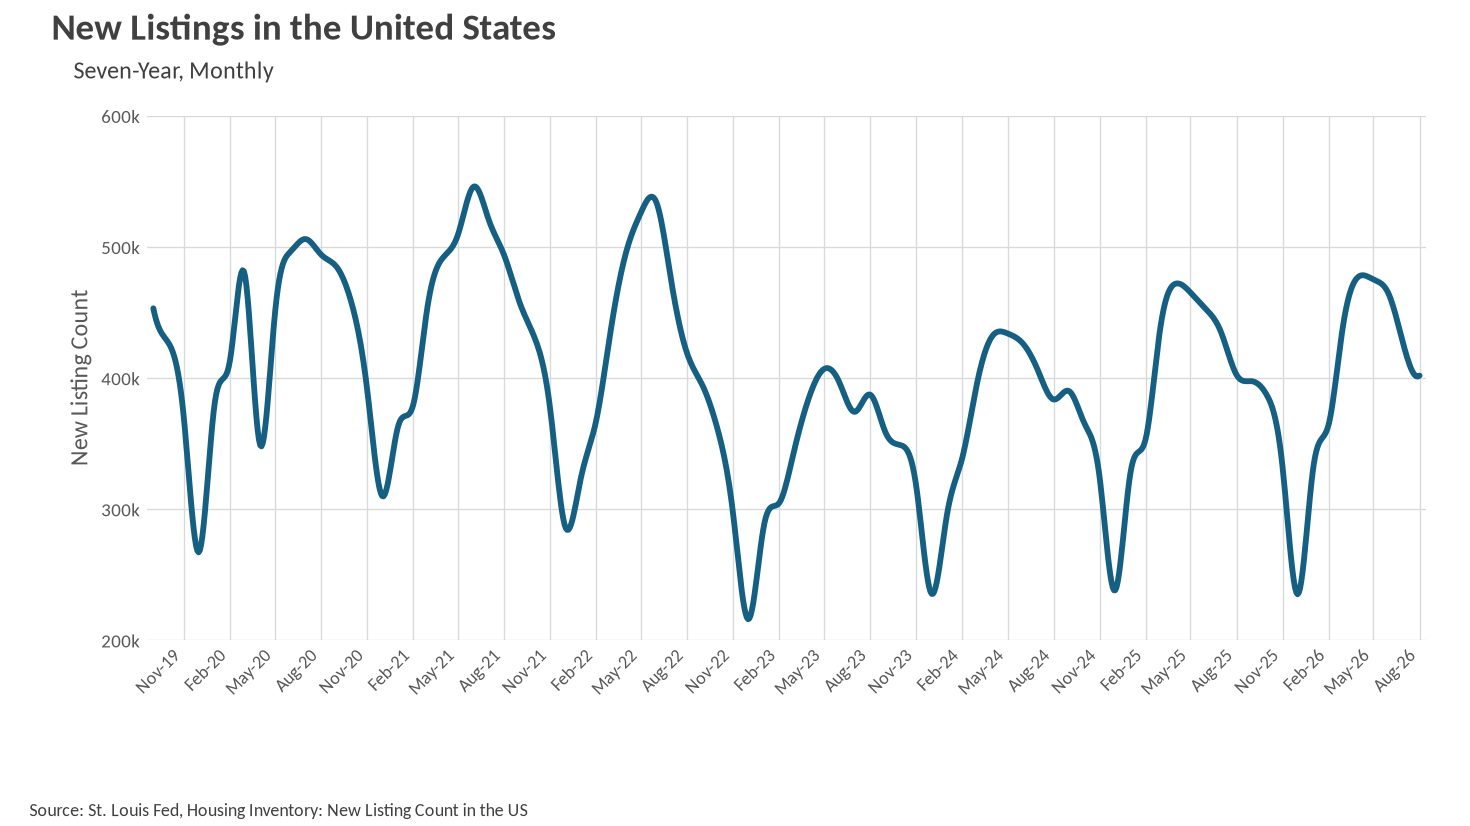
Inventory did not plateau after all. After holding flat at 1,570,000 homes for three consecutive months from May through July, inventory jumped to 1,620,000 in August, a 3.18% month-over-month increase and a 5.88% gain over the 1,530,000 homes available at this time last year. That is the highest inventory level anywhere in this data series, and it represents a 31.7% increase from the December low of 1,230,000. What makes this build particularly notable is that it is not being driven by a flood of new supply. New listings actually fell to 401,760 in August, down 5.18% from July's 423,732 and essentially flat compared to the 402,276 new listings we saw in August of last year. So sellers are not listing more aggressively than they were a year ago. Instead, inventory is accumulating because homes are not clearing at the pace they once did. That distinction matters, because supply that builds from weak absorption tends to be stickier and puts more direct pressure on pricing than supply that builds from a surge of eager sellers.
Existing home sales have slipped below last year's pace
Existing home sales came in at 3,980,000 in August, a 1.97% month-over-month decline from July's 4,060,000 and a 1.24% drop from the 4,030,000 pace we saw in August of last year. This is the weakest sales figure in the data we have, and it marks a clear reversal from the spring, when sales were running above the prior year and reached 4,190,000 in May. The culprit is not hard to identify. Buyers who were enjoying sub-$2,000 monthly payments in January are now looking at $2,256, and mortgage rates that started the year at 6.16% are now sitting at 6.71%. When financing costs move that much in nine months, the marginal buyer simply steps out of the market, and that is exactly what the sales data is showing. Three consecutive months of declining sales, combined with inventory pushing to new highs, tells us that the balance of the market has shifted in a way it had not through the first half of the year. The question now is whether rates stabilize and let buyers re-engage this fall, or whether we continue to see demand erode into the winter.
Buyers are gaining leverage for the first time in a while
When determining whether a market is a buyers’ market or a sellers’ market, we look to the Months of Supply Inventory (MSI) metric. The state of California has historically averaged around three months of MSI, so any area with at or around three months of MSI is considered a balanced market. Any market that has lower than three months of MSI is considered a seller’s market, whereas markets with more than three months of HSI is considered buyers’ markets.
At the national level, the numbers point clearly toward a buyers' market. With 1,620,000 homes for sale in August against an annualized sales pace of 3,980,000, the implied months of supply works out to roughly 4.9 months, comfortably above the three-month threshold that separates balanced markets from buyers' markets. A year ago, that same calculation produced about 4.6 months, so supply has loosened meaningfully over the past twelve months. Every component of the equation is currently moving in buyers' favor: inventory is at a cycle high and rising, sales are falling on both a monthly and annual basis, and median prices have declined for two straight months. The obvious catch is affordability. Buyers may have more negotiating room and more homes to choose from than at any point in recent memory, but with rates at 6.71% and monthly payments up more than $300 since January, the cost of taking advantage of that leverage has risen sharply. Sellers, for their part, should expect longer marketing times and more price sensitivity than they saw this spring. As always, real estate is a highly localized asset, which is why you should check out what's going on in your local market below in the Local Lowdown!
Big Story Data
The Local Lowdown
Quick Take:
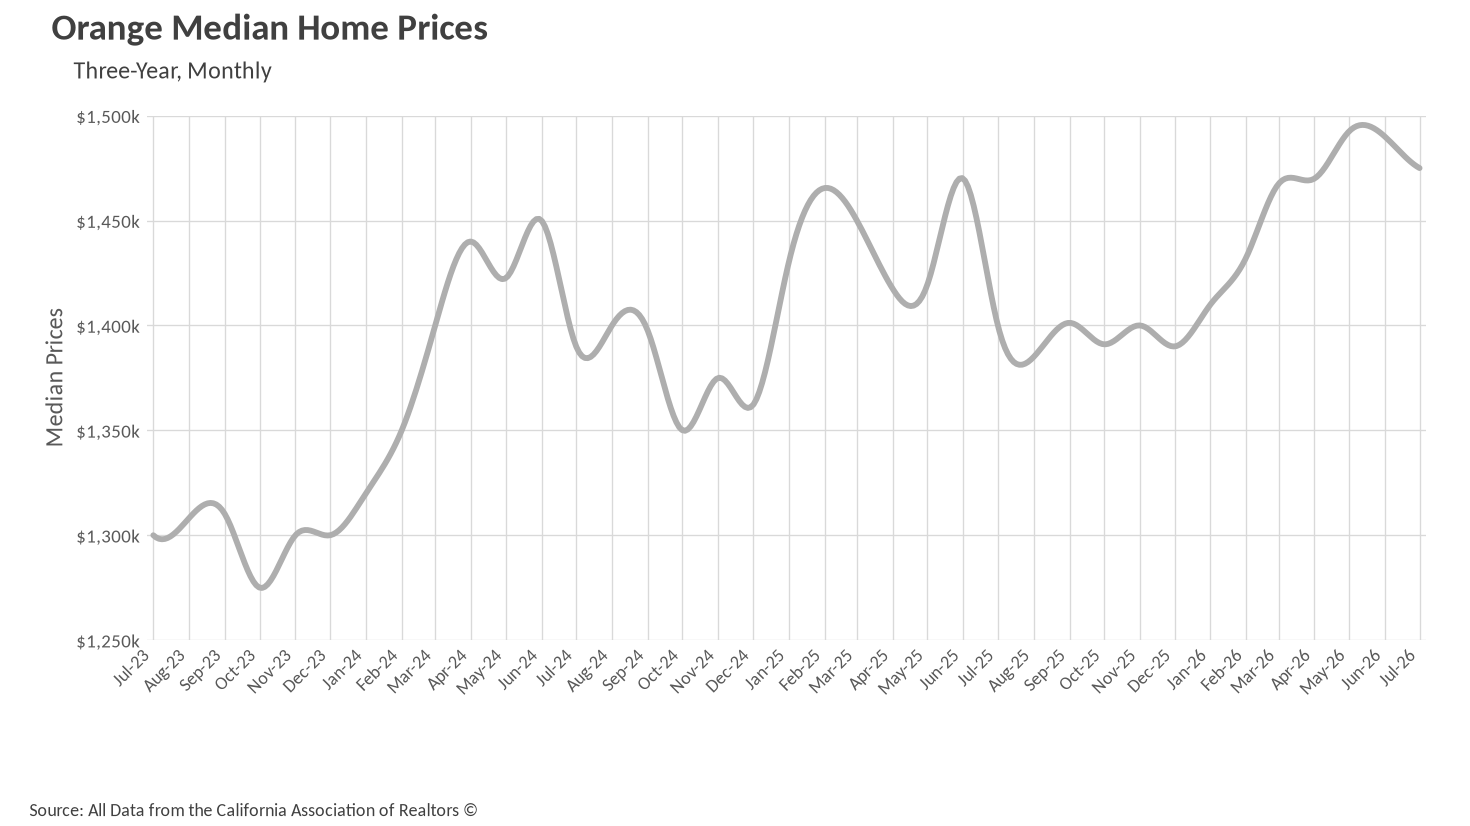
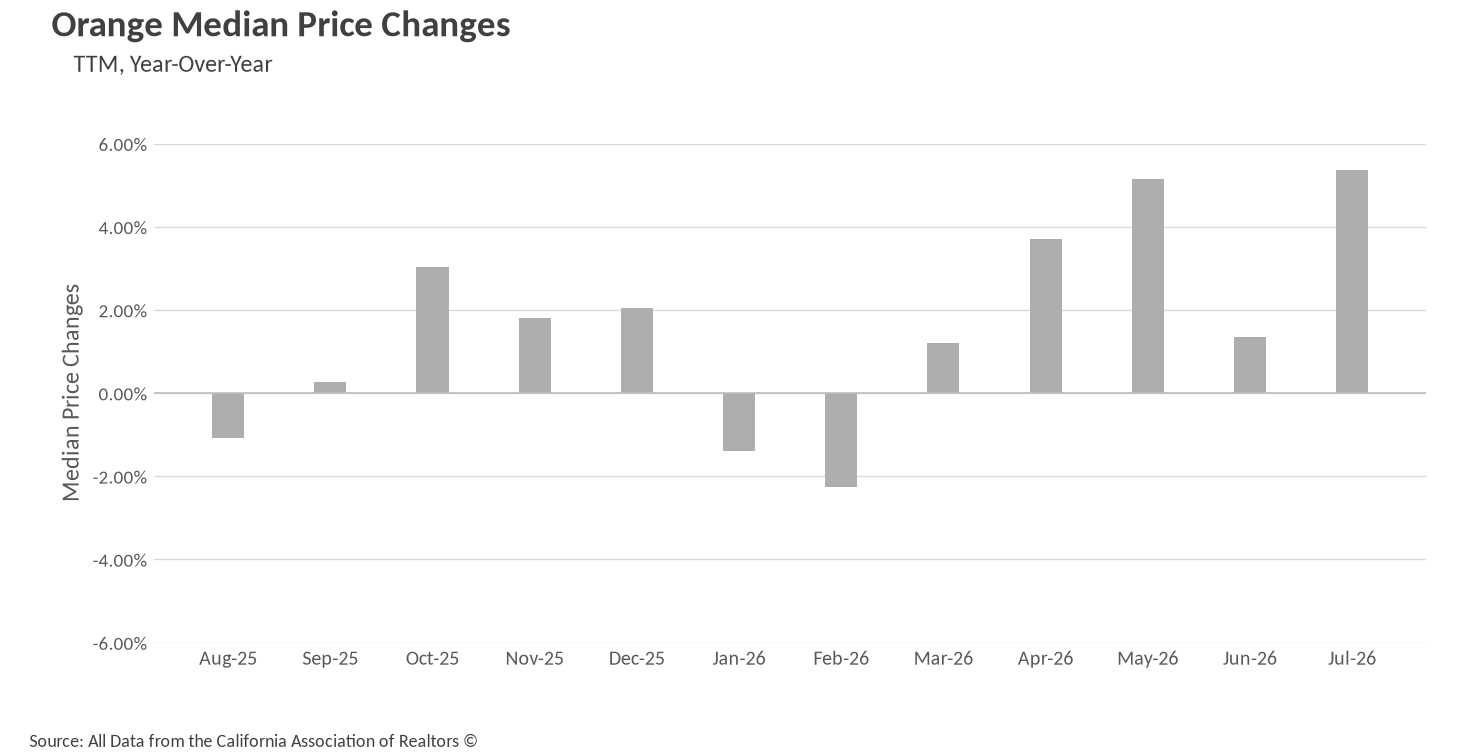
- The median single-family home in Orange County sold for $1,475,000 in July, a 5.36% jump over last July and the strongest year-over-year gain of 2026 so far.
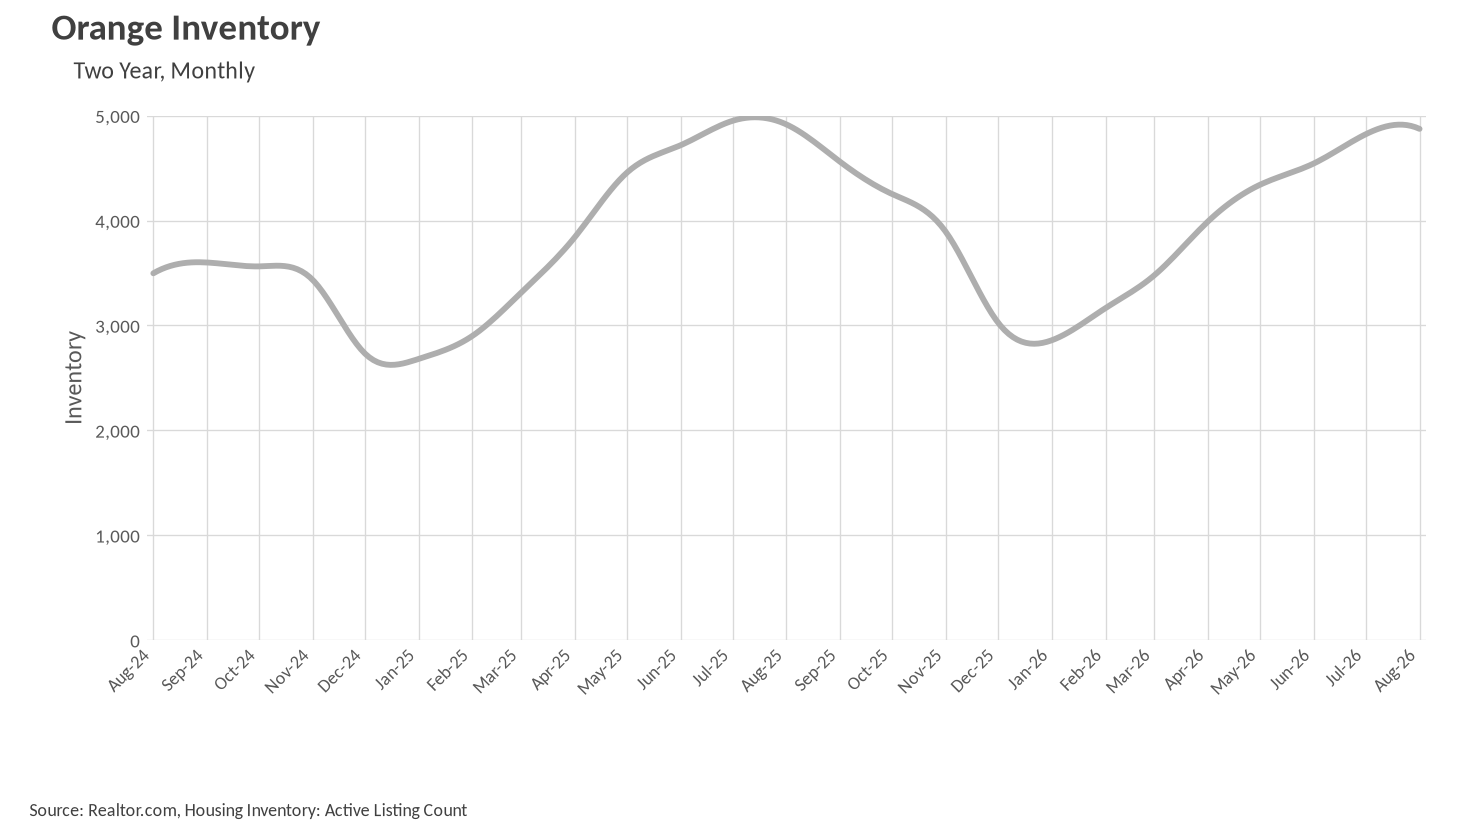
- Inventory has now come in below year-ago levels for four straight months, with August's 4,874 active listings sitting 0.85% under last August.
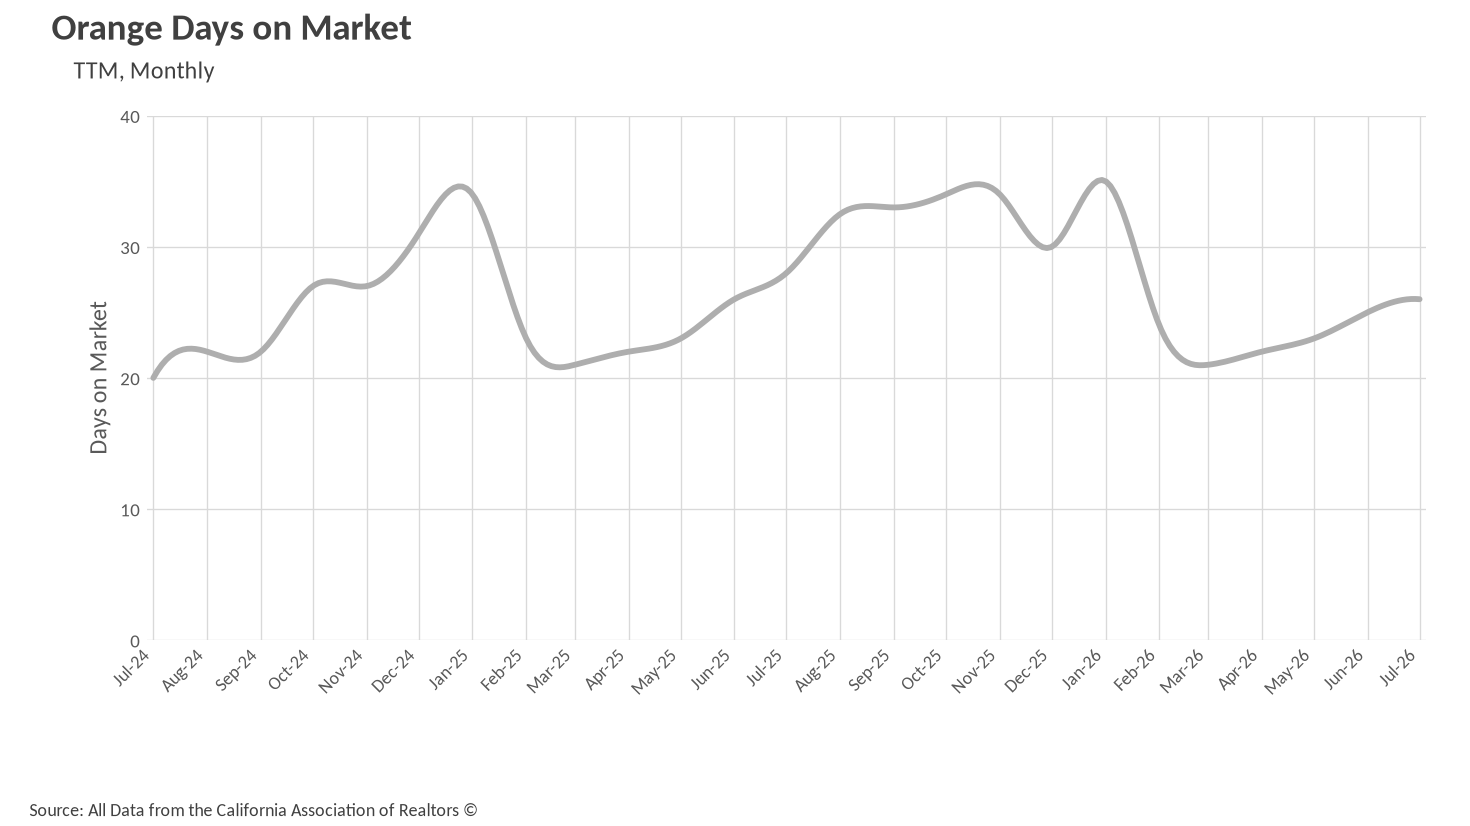
- Listings are moving faster than they were a year ago, with the median listing spending 26 days on the market in July, down from 28 days last July.
Note: You can find the charts/graphs for the Local Lowdown at the end of this section.
Prices ease off the spring peak but still tower over last summer
Orange County's median single-family home price landed at $1,475,000 in July, down a slight 1.01% from June's $1,490,000 but up a substantial 5.36% compared to July of last year. That year-over-year figure is the largest we have recorded all year, edging out the 5.14% gain posted in May. It also makes July 2026 the strongest July in our data set by a wide margin, coming in well above the $1,400,000 median recorded in July 2025 and the $1,390,000 median from July 2024.
What stands out here is the durability of the trend. Orange County has now posted five consecutive months of year-over-year price appreciation, running from 1.21% in March to 3.71% in April, 5.14% in May, 1.36% in June, and now 5.36% in July. The month-to-month movement has been choppy, which is typical as the mix of homes changing hands shifts through the season, but the direction of travel is unmistakable. Last summer, prices slid from $1,470,000 in June down to $1,400,000 in July and $1,385,000 in August. This year, the summer pullback has been far shallower, which suggests underlying demand is holding up better than it did twelve months ago.
Inventory keeps building, but it can't catch last year's pace
August brought 4,874 active single-family listings to the Orange County market, the highest count of 2026 and a 1.06% increase over July's 4,823. That is the smallest month-over-month gain we have seen since the winter trough, a notable deceleration from the double-digit percentage increases recorded back in the February through April stretch. Inventory is still growing, but the growth is flattening out as we move past the seasonal peak.
The more meaningful story is the year-over-year comparison. August's total came in 0.85% below the 4,916 listings on the market in August 2025, marking the fourth consecutive month that Orange County inventory has trailed year-ago levels. May was down 2.58%, June down 3.69%, and July down 2.59%. These are not dramatic declines, but they represent a genuine shift from the first part of the year when inventory was running ahead of 2025. With supply plateauing rather than piling up, sellers heading into the fall are facing less competition than their counterparts did last year.
Listings are finding buyers a little quicker than last summer
The median Orange County single-family listing spent 26 days on the market in July, up 4% from June's 25 days. That modest uptick is a normal seasonal pattern as the urgency of the spring rush fades, and it is a far cry from the 35 days we recorded back in January.
More encouraging is the comparison to last year. July 2025 saw a median of 28 days on market, meaning this July's pace is 7.14% faster. This is the second straight month of year-over-year improvement, following June's 25 days against 26 days a year earlier. For context, last summer marked the beginning of a sustained slowdown, with days on market climbing from 28 in July to 32.5 in August and 34 by October. If this year's trajectory holds closer to the mid-20s through the back half of the season, it would signal meaningfully healthier absorption than we saw in 2025. For now, buyers still have enough breathing room to be deliberate, while sellers who price realistically are seeing activity within about three and a half weeks.
Orange County holds its balance, with a tilt toward sellers
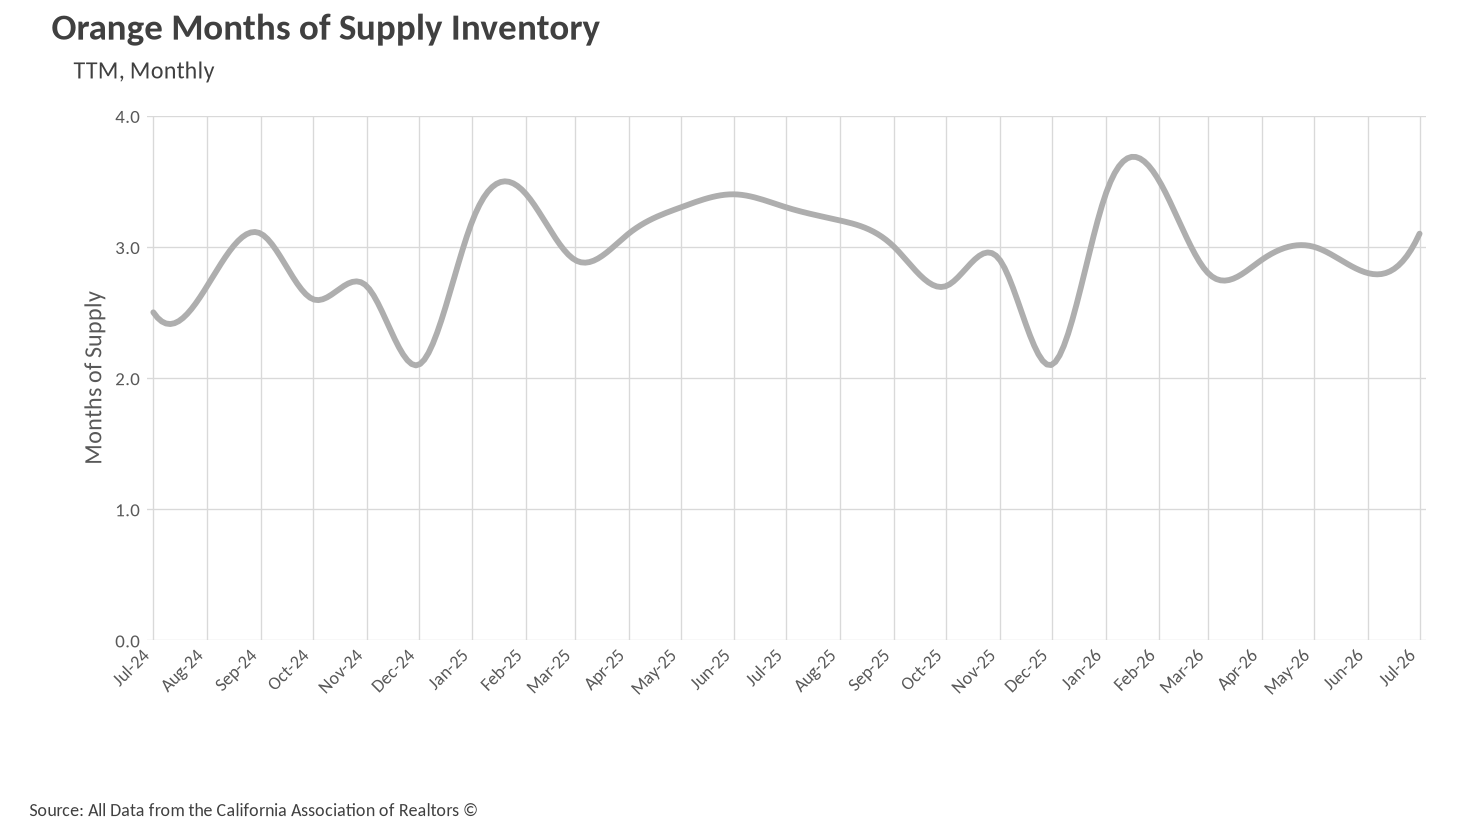
When determining whether a market is a buyers’ market or a sellers’ market, we look to the Months of Supply Inventory (MSI) metric. The state of California has historically averaged around three months of MSI, so any area with at or around three months of MSI is considered a balanced market. Any market that has lower than three months of MSI is considered a seller’s market, whereas markets with more than three months of MSI are considered buyers’ markets.
Orange County registered 3.1 months of supply in July, placing it squarely in balanced territory with only the faintest lean toward buyers. That figure is up 10.71% from June's 2.8 months, reflecting the seasonal inventory build, but it is down 6.06% from the 3.3 months recorded in July 2025. Zooming out, MSI has hovered in a narrow band between 2.8 and 3.1 months every month since March, a remarkable stretch of stability after the 3.4 and 3.5 month readings that opened the year.
The takeaway is that neither side holds a decisive advantage right now, but the underlying momentum favors sellers. Prices are appreciating at their fastest year-over-year clip of 2026, inventory has trailed year-ago levels for four consecutive months, and homes are selling faster than they did last summer. If inventory continues its typical autumn decline while demand holds steady, Orange County could slip back under the three month mark and into seller's market territory before the year is out.