The Big Story
Quick Take:
- Median home sale prices slipped for a fourth consecutive month in October, though they remain modestly above where they were a year ago.
- Inventory ticked up to its highest level of the year in October after holding flat for five straight months.
- Existing home sales fell to their weakest pace in over a year as mortgage rates jumped above 7%, pushing monthly payments to a new high.
Note: You can find the charts & graphs for the Big Story at the end of the following section.
*National Association of REALTORS® data is released two months behind, so we estimate the most recent month's data when possible and appropriate.
The spring rally has given way to an autumn cooldown
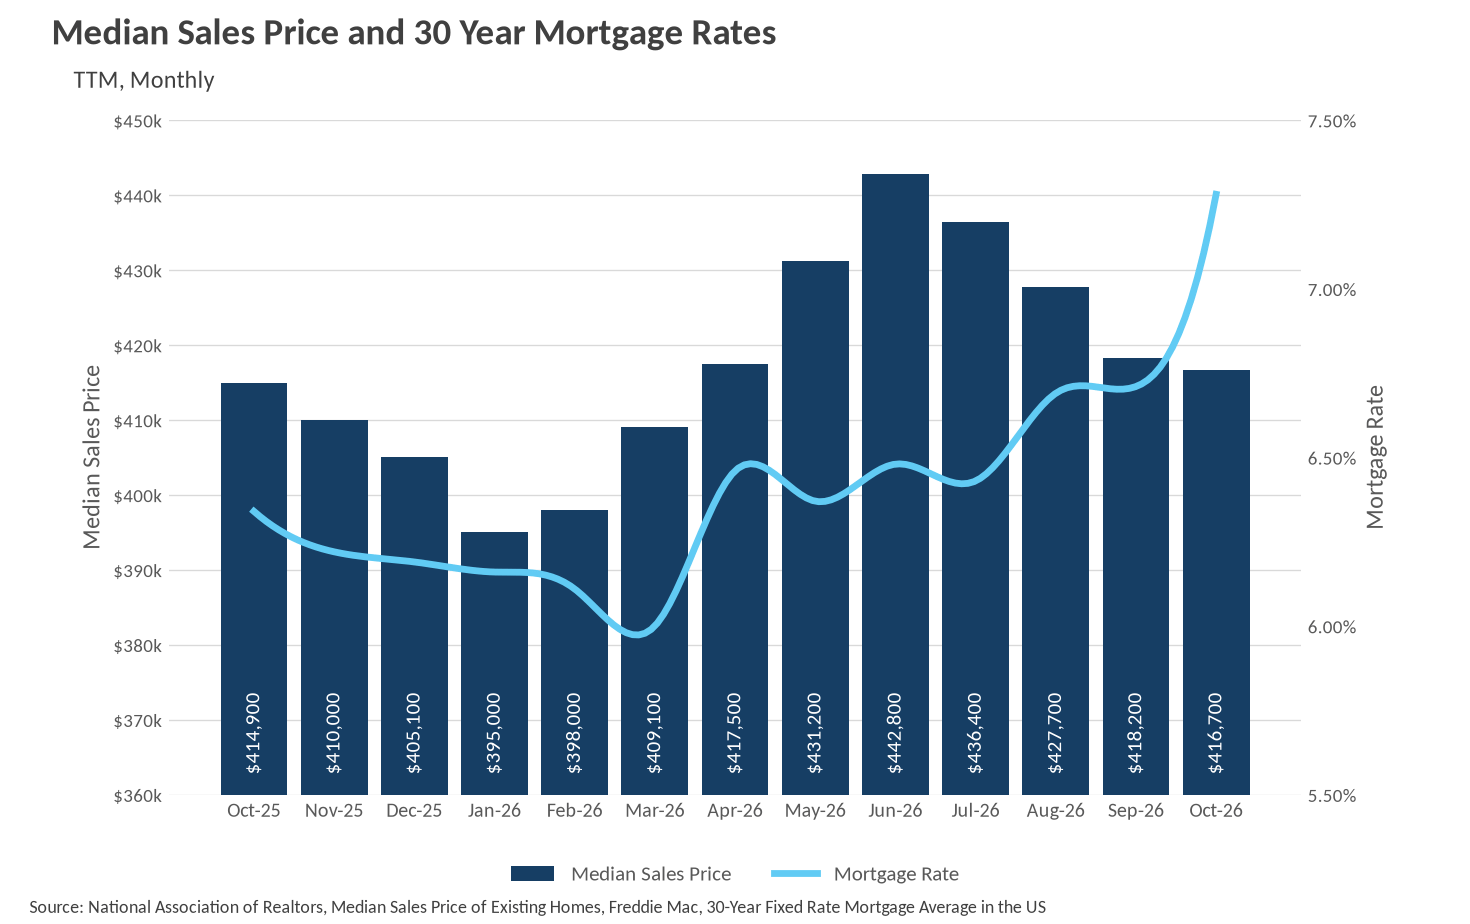
After median sale prices climbed all the way to $442,800 in June, the market has spent the back half of the year giving those gains back. In October, the median home sold for $416,700, a 0.36% month-over-month decline from September's $418,200 and the fourth consecutive monthly step down. All told, prices have retreated 5.90% from the June peak. The one silver lining is that the year-over-year comparison is still positive, if only barely: October 2025 saw a median of $414,900, which puts current prices 0.43% higher than a year ago.
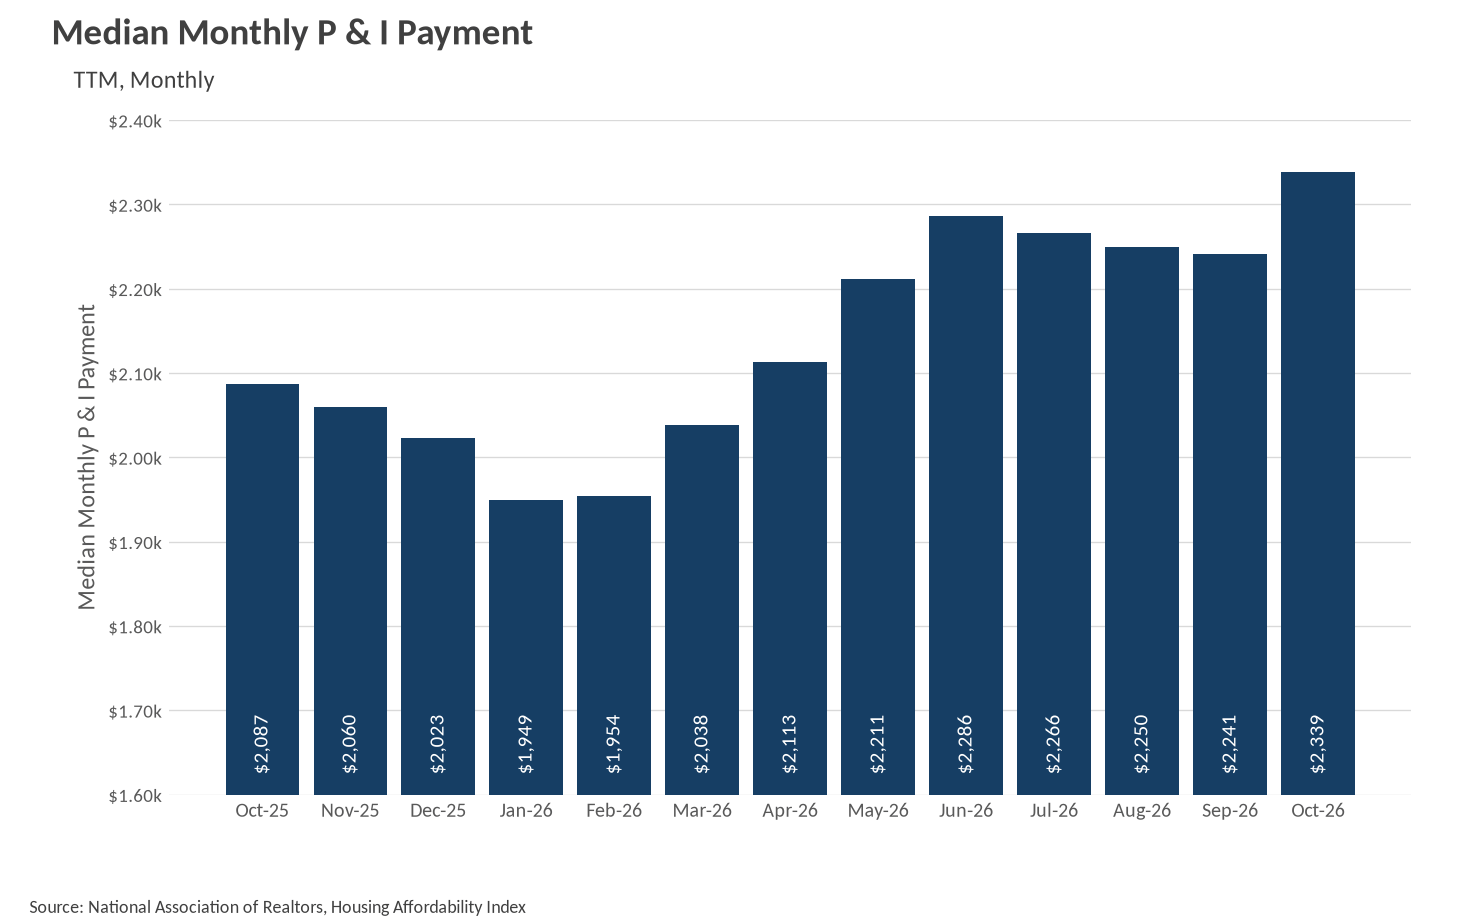
The affordability story, however, has gone from concerning to genuinely difficult. Mortgage rates surged to 7.28% in October, up sharply from 6.71% in September and a world away from the 6.00% floor we saw in March. Rates did pull back slightly to 7.18% in November, which is the most current reading we have, but that is small comfort. The result is that even with prices falling, the median monthly principal and interest payment rose to $2,339 in October, up 4.37% from September and 12.07% above the $2,087 buyers were paying last October. Put differently, the median payment has climbed just over 20% from January's $1,949 low, even though the median sale price is up only 5.49% over that same stretch. This is a rate-driven affordability squeeze, plain and simple, and falling prices have not been enough to offset it.
Inventory climbs to its highest level of the year
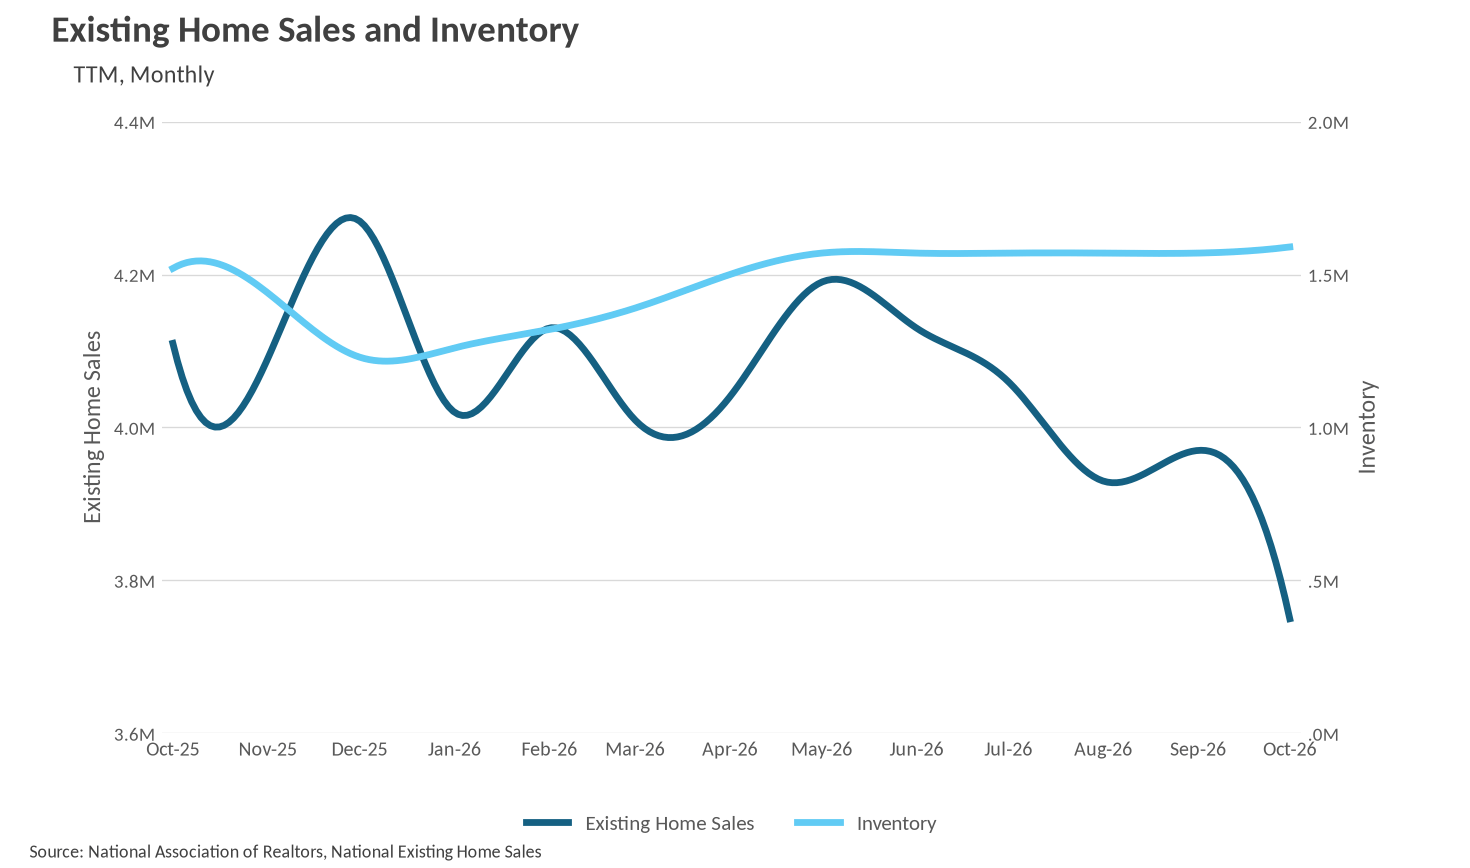
Inventory had been remarkably static through the middle of the year, holding at exactly 1,570,000 homes from May through September. That streak broke in October, when inventory rose to 1,590,000, a 1.27% month-over-month increase and the highest level we have seen in this data set. Compared to the 1,520,000 homes available last October, supply is up 4.61% year-over-year, and it sits 29.27% above the December 2025 trough of 1,230,000.
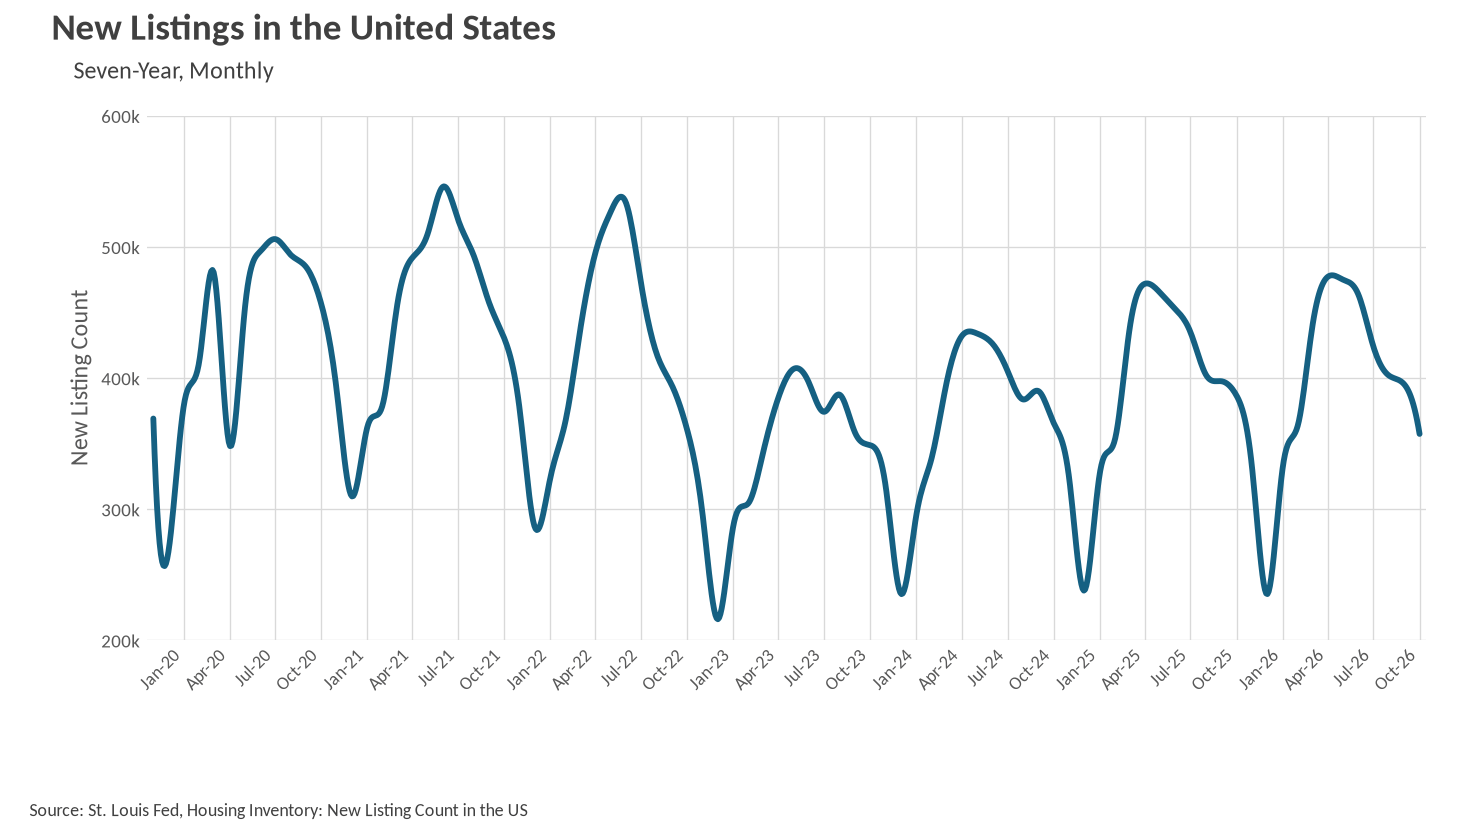
What makes that increase notable is that it is not coming from sellers flooding the market. New listings actually fell to 357,268 in October, down 9.51% from September and down 7.54% from the 386,414 new listings we saw in October 2025. Sellers are pulling back, not leaning in. Inventory is building because homes are sitting, not because more of them are being listed. That is a meaningful distinction, because it tells us the supply story is really a demand story in disguise. Seasonally, we would expect both new listings and total inventory to recede through the winter, so the fact that inventory grew in October is a signal worth watching closely.
Existing home sales hit their slowest pace in more than a year
Existing home sales came in at 3,750,000 in October, a 5.54% drop from September's 3,970,000 and an 8.76% decline from the 4,110,000 pace recorded last October. That is the weakest reading in this entire series, and it caps a steady deterioration that began after sales peaked at 4,190,000 in May. Sales have now fallen in four of the last five months.
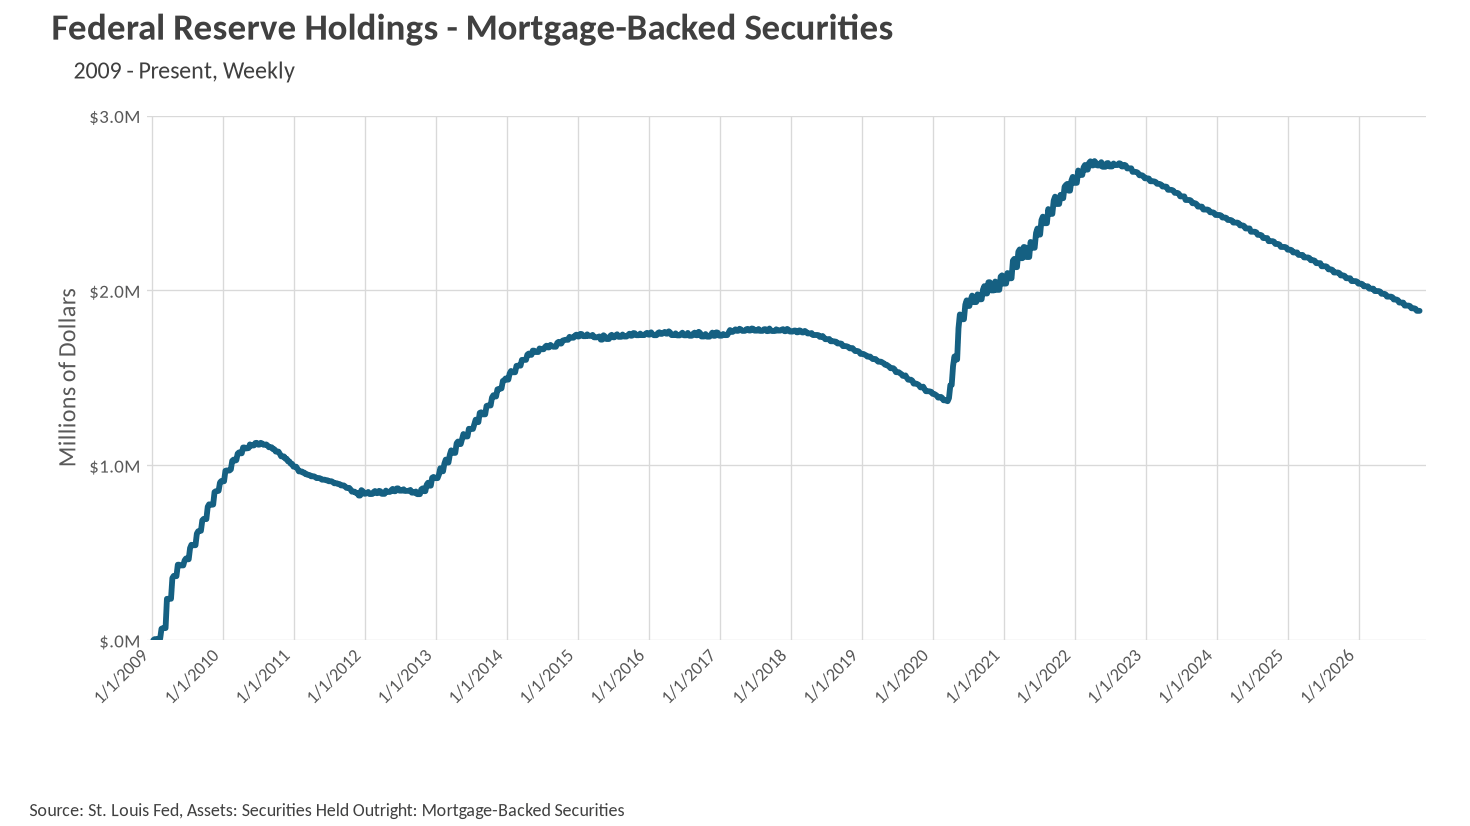
The timing lines up almost perfectly with the move in rates. Through the spring, when rates sat between 6.00% and 6.48%, sales held in the 4,000,000 to 4,190,000 range. Once rates pushed through 6.69% in August and then spiked to 7.28% in October, buyers stepped back in a hurry. One factor worth keeping an eye on is the Federal Reserve's mortgage-backed securities portfolio, which has continued to run off steadily, falling from roughly $2.024 trillion in February to $1.884 trillion as of November. With the Fed shrinking its footprint in the mortgage market, there is less support holding mortgage rates down relative to Treasury yields, which helps explain why borrowing costs have been so stubborn even as home prices soften.
Supply is building faster than buyers can absorb it
When determining whether a market is a buyers’ market or a sellers’ market, we look to the Months of Supply Inventory (MSI) metric. The state of California has historically averaged around three months of MSI, so any area with at or around three months of MSI is considered a balanced market. Any market that has lower than three months of MSI is considered a seller’s market, whereas markets with more than three months of MSI are considered buyers’ markets.
Nationally, the math has clearly shifted toward buyers. With 1,590,000 homes available in October against an annualized sales pace of 3,750,000, the market is carrying roughly 5.1 months of supply, comfortably above the three-month balanced threshold. Compare that to June, when 1,570,000 homes and a 4,130,000 sales pace worked out to about 4.6 months, and the direction of travel is unmistakable. Rising inventory, falling sales, and four straight months of price declines all point the same way. The counterweight is that sellers are not being forced to list, as evidenced by new listings falling nearly 10% month-over-month, which should keep supply growth in check and prevent prices from falling off a cliff. If rates continue easing from the 7.28% October peak toward November's 7.18% and beyond, demand could stabilize quickly. As always, real estate is a highly localized asset, which is why you should check out what's going on in your local market below in the Local Lowdown!
Big Story Data
 The Local Lowdown
Quick Take:
- Median sale prices rebounded in September, with the median single-family home selling for $1,480,000, a 5.62% jump over last year and the strongest year-over-year gain of 2026 so far.
- Inventory has flipped back above last year's levels, with October's 4,692 active listings running 10.35% higher than the same month in 2025.
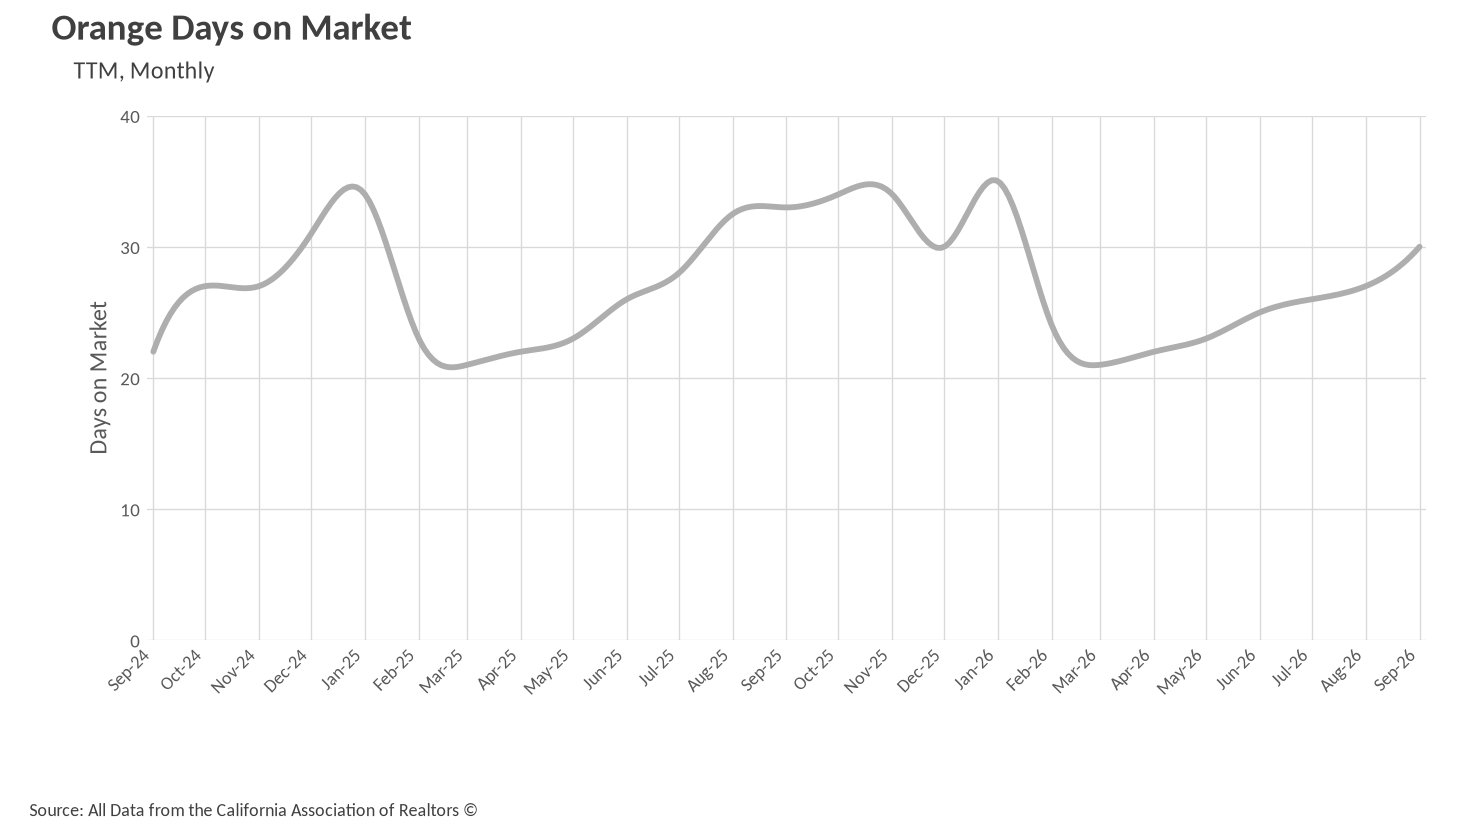
- Listings are still moving faster than they did a year ago, with the median home spending 30 days on the market in September, down 9.09% year over year.
Note: You can find the charts/graphs for the Local Lowdown at the end of this section.
Prices find their footing again after a summer slide
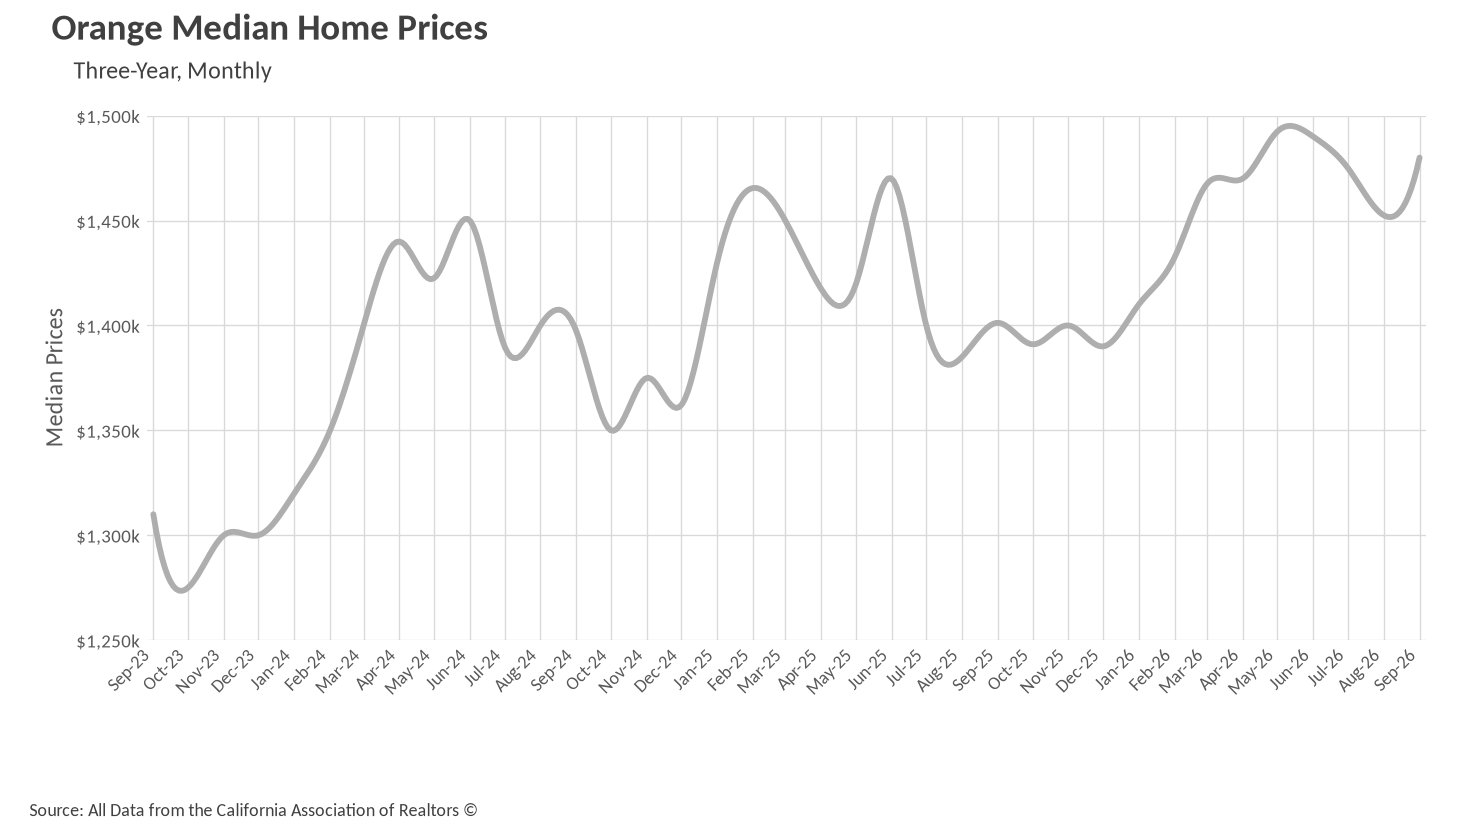
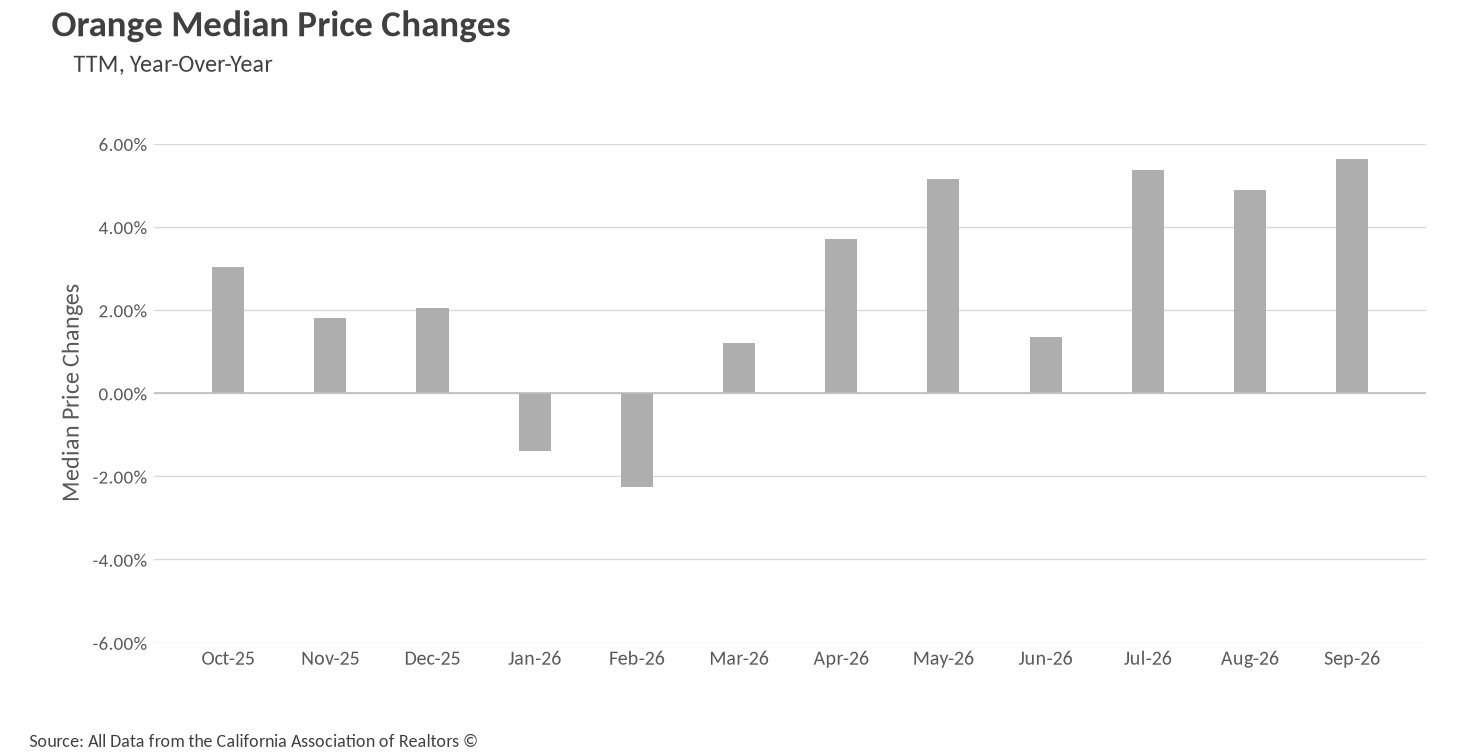
After drifting lower for three straight months, Orange County's median sale price turned around in September. The median single-family home sold for $1,480,000, a 1.89% increase over August and a 5.62% gain compared to September 2025. That year-over-year figure is the largest we have recorded this year, outpacing the 4.87% posted in August and the 5.36% in July. What makes this rebound notable is the context: prices peaked in May at $1,492,500, then eased through June, July, and August, bottoming out at $1,452,500 before September's bounce. Rather than signaling a cooling market, that summer dip now looks like typical seasonal softness layered on top of a steadily rising base. Zoom out and the trend is unmistakable. Two years ago, in September 2024, the median sat at $1,397,450, and the year before that it was $1,310,000. Orange County has added roughly $170,000 to its median sale price over that span, and the pace of appreciation has quietly been accelerating since the spring.
Inventory is building again, and it is no longer following last year's script
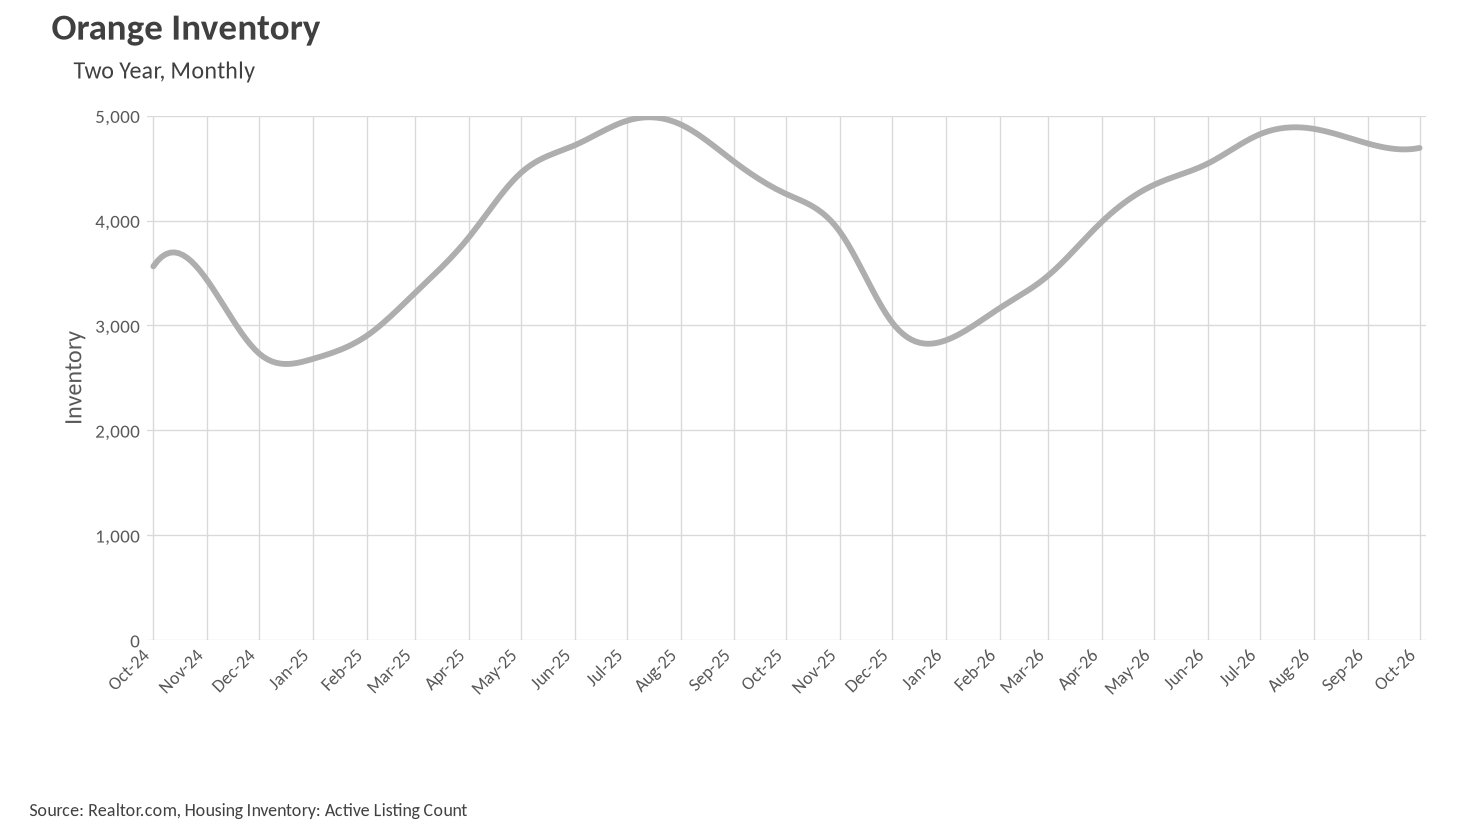
October brought 4,692 active single-family listings to the Orange County market, a 10.35% increase over the 4,252 listings available in October 2025. That is the second consecutive month in which inventory has exceeded year-ago levels, following September's 3.86% year-over-year gain, and it marks a clear reversal from the summer, when inventory was running below 2025 in June, July, and August. The more revealing story is in the month-over-month movement. Inventory slipped just 0.91% from September to October, while last year the same stretch saw a 6.7% drawdown. In other words, the usual autumn clearing out of listings simply is not happening with the same force this time around. Supply peaked in August at 4,874 and has barely budged since, which suggests sellers are holding firm on price and allowing listings to sit rather than pulling them off the market. Buyers heading into the fall and winter should find meaningfully more to choose from than they did a year ago.
Homes are still selling faster than they did last fall
Days on market climbed to 30 in September, up 11.11% from August's 27 days, which is exactly the seasonal pattern we would expect as the spring and summer rush fades. The more important comparison is against last year, and on that front the market continues to look healthier. September 2025 saw a median of 33 days, so this year's 30 days represents a 9.09% improvement. That extends a streak that has held all summer, with August down 16.92% year over year, July down 7.14%, and June down 3.85%. Even as listings pile up, the ones that are priced correctly are finding buyers more efficiently than they did in 2025. For context, days on market bottomed out at 21 in March before climbing steadily through the spring and summer, and last year the metric pushed all the way to 34 in October and November before peaking at 35 in January. If the current year-over-year advantage holds, Orange County should avoid the worst of that winter slowdown.
A market sitting squarely on the fence
When determining whether a market is a buyers’ market or a sellers’ market, we look to the Months of Supply Inventory (MSI) metric. The state of California has historically averaged around three months of MSI, so any area with at or around three months of MSI is considered a balanced market. Any market that has lower than three months of MSI is considered a seller’s market, whereas markets with more than three months of MSI are considered buyers’ markets.
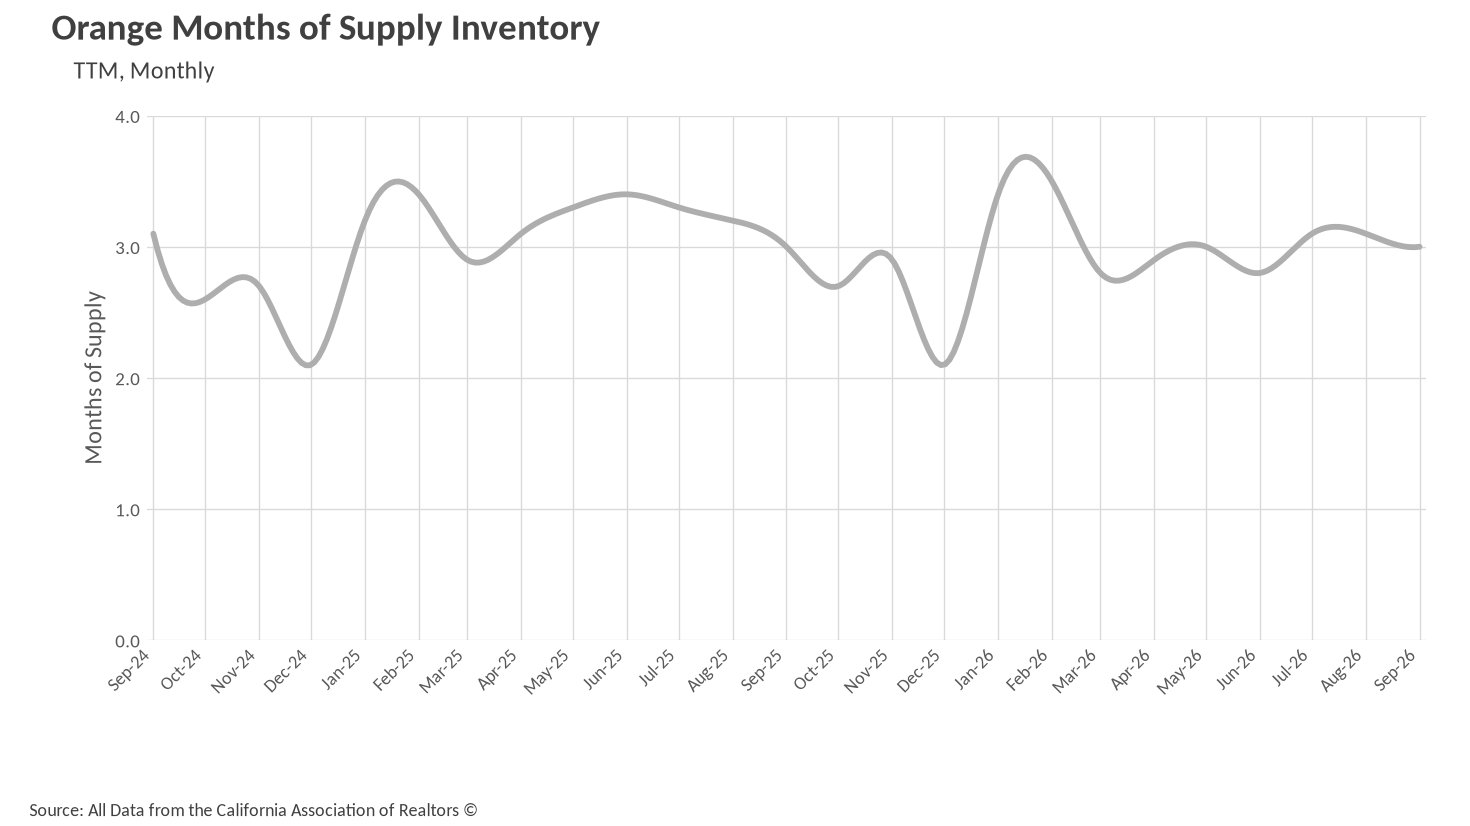
Orange County closed September with exactly 3.0 months of supply, placing it right at the center of balanced territory. That is a 3.23% decrease from August's 3.1 months and perfectly flat against September 2025, which also registered 3.0 months. The remarkable thing about this market is how little the MSI needle has moved all year. Since March, Orange County has oscillated in a narrow band between 2.8 and 3.1 months, never tipping decisively toward either camp. Sellers can take comfort in the fact that prices are appreciating at the fastest clip of the year and homes are selling roughly three days quicker than they did last fall. Buyers, meanwhile, have the growing inventory pile on their side, with October listings up more than 10% year over year and showing no signs of the usual seasonal retreat. Heading into the winter, expect this market to stay close to equilibrium, though the inventory build is the trend worth watching most closely.