The Big Story
Quick Take:
-
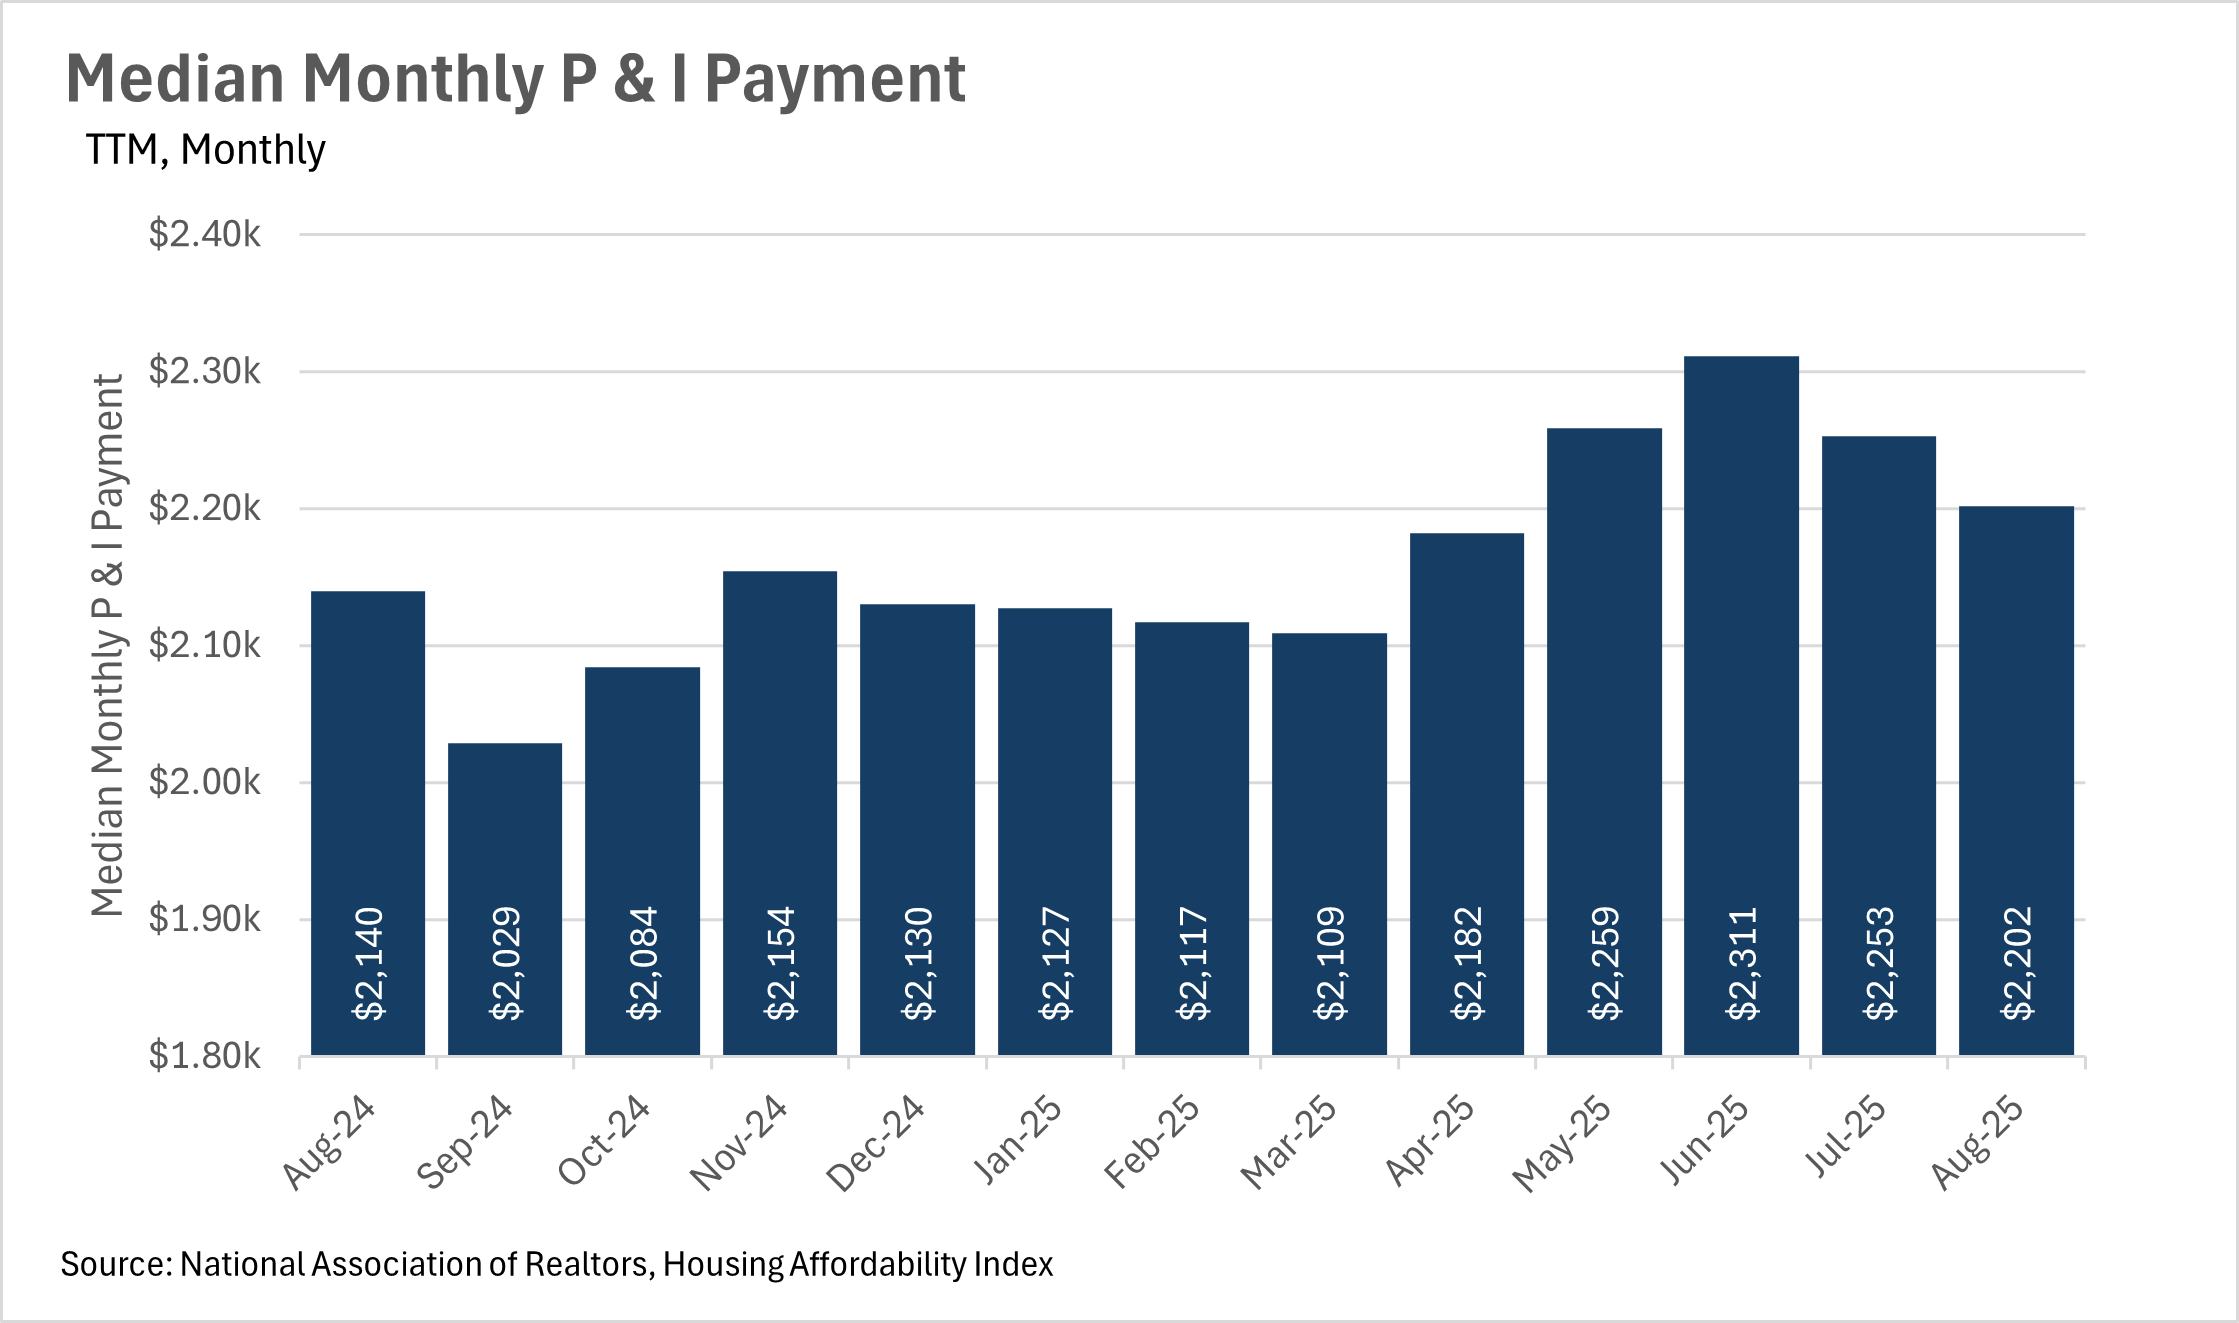
Affordability remains an issue nationwide, as monthly P&I payments ticked up by 2.90% year-over-year.
-
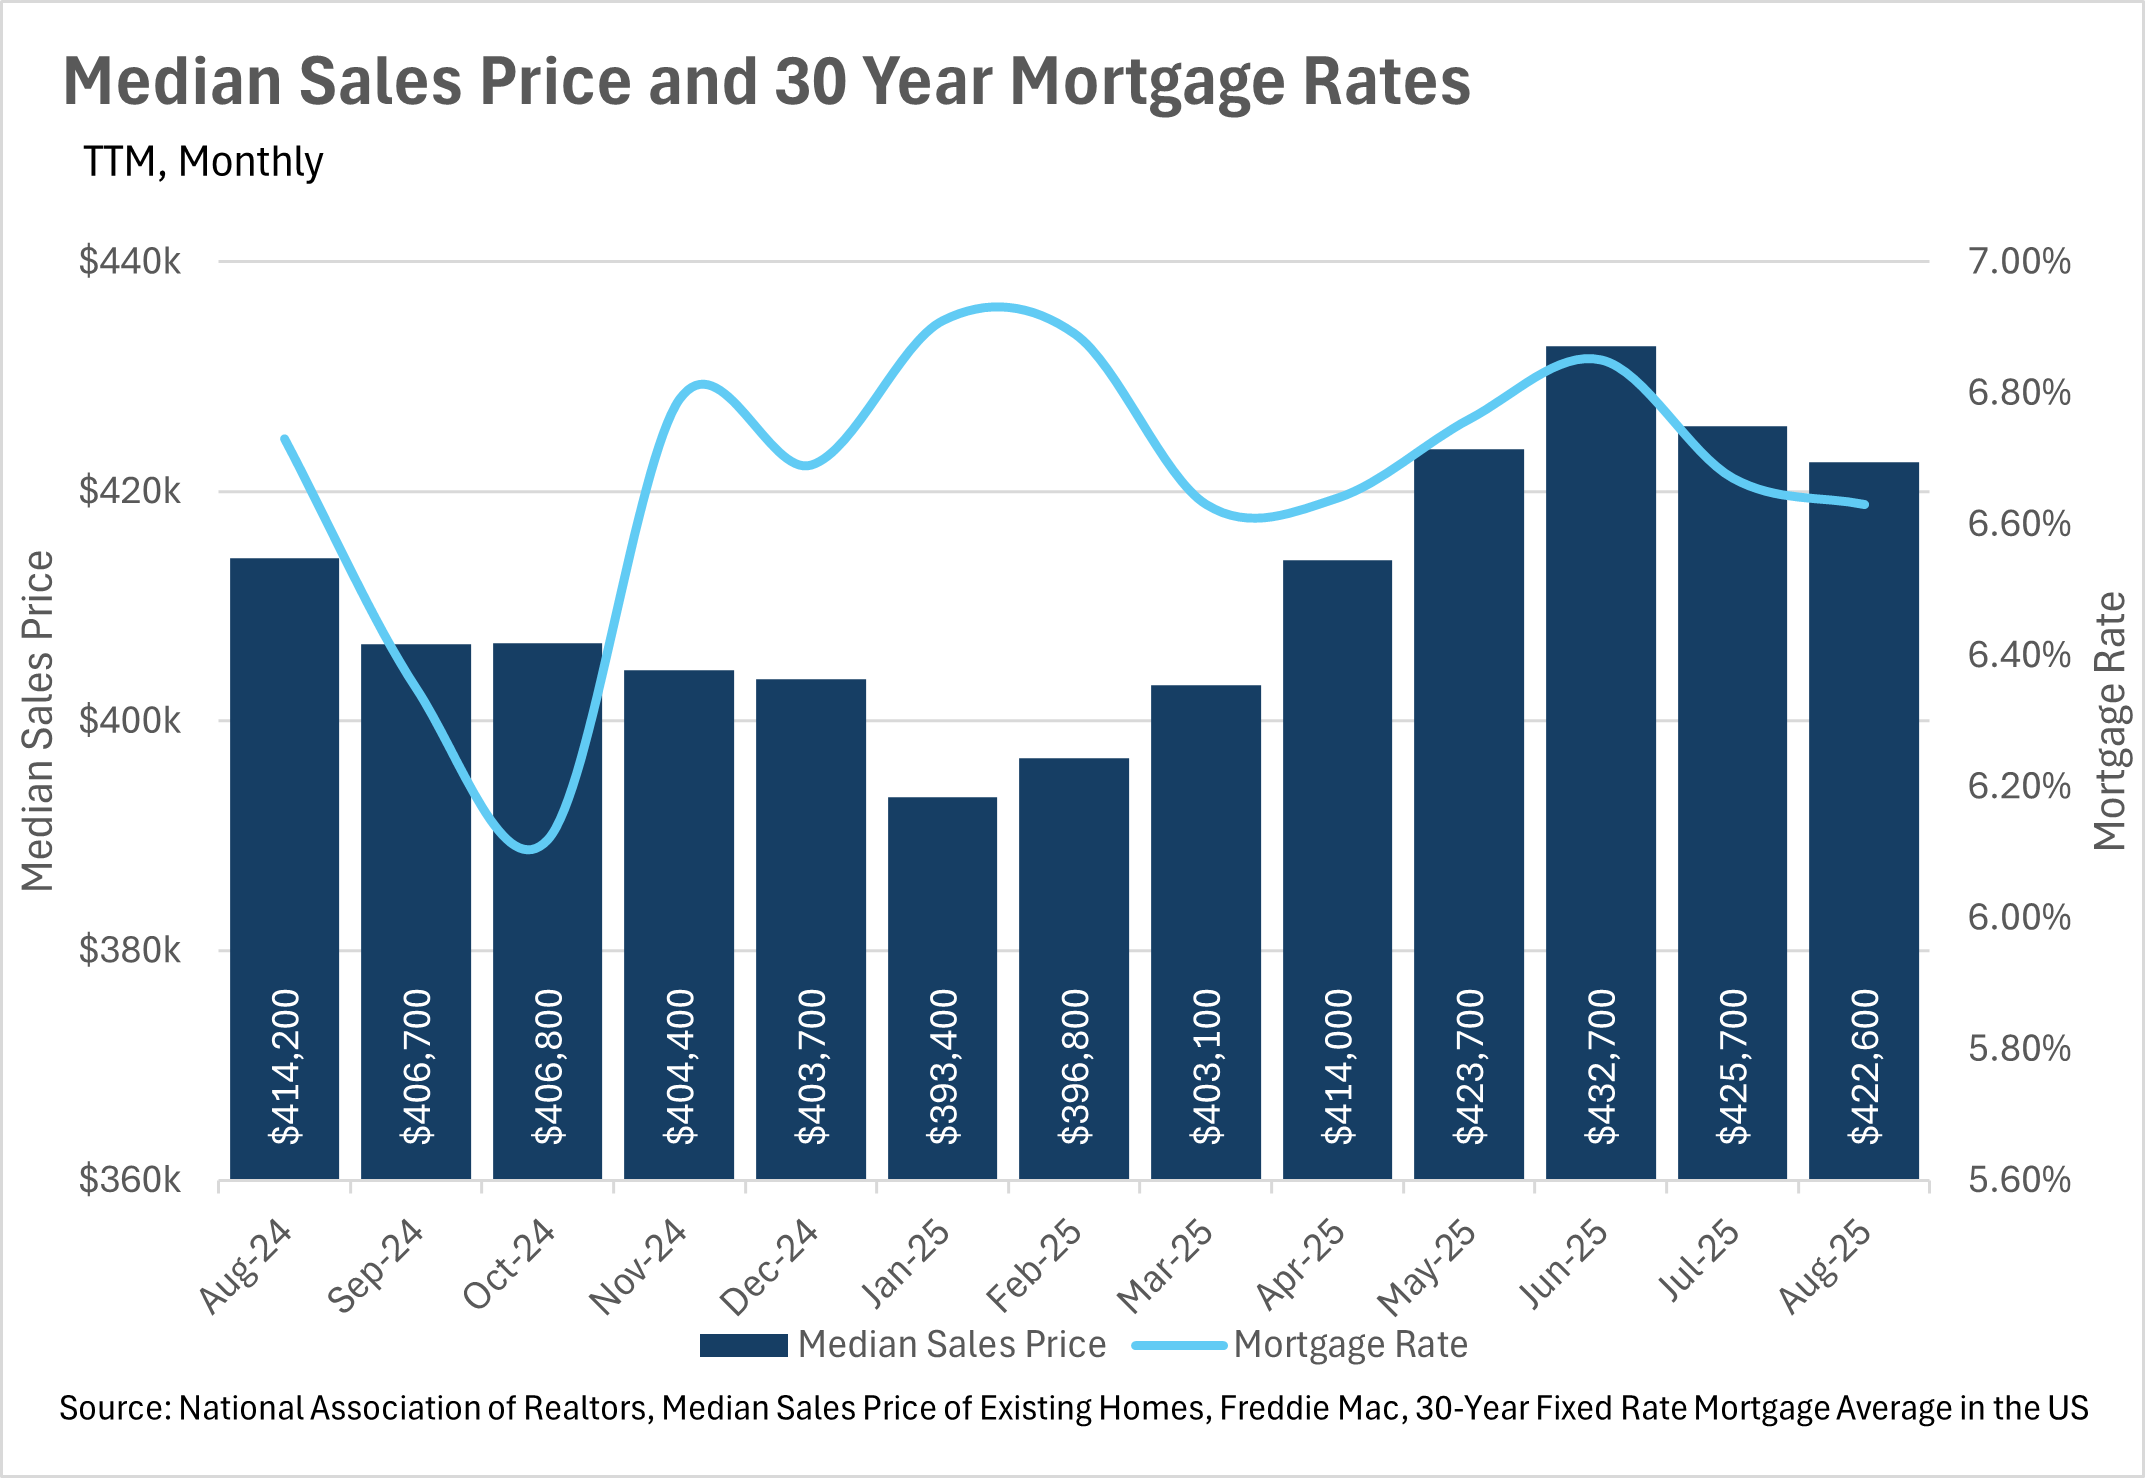
Mortgage rates are finally starting to decline, as we enter a rate-cutting cycle.
-
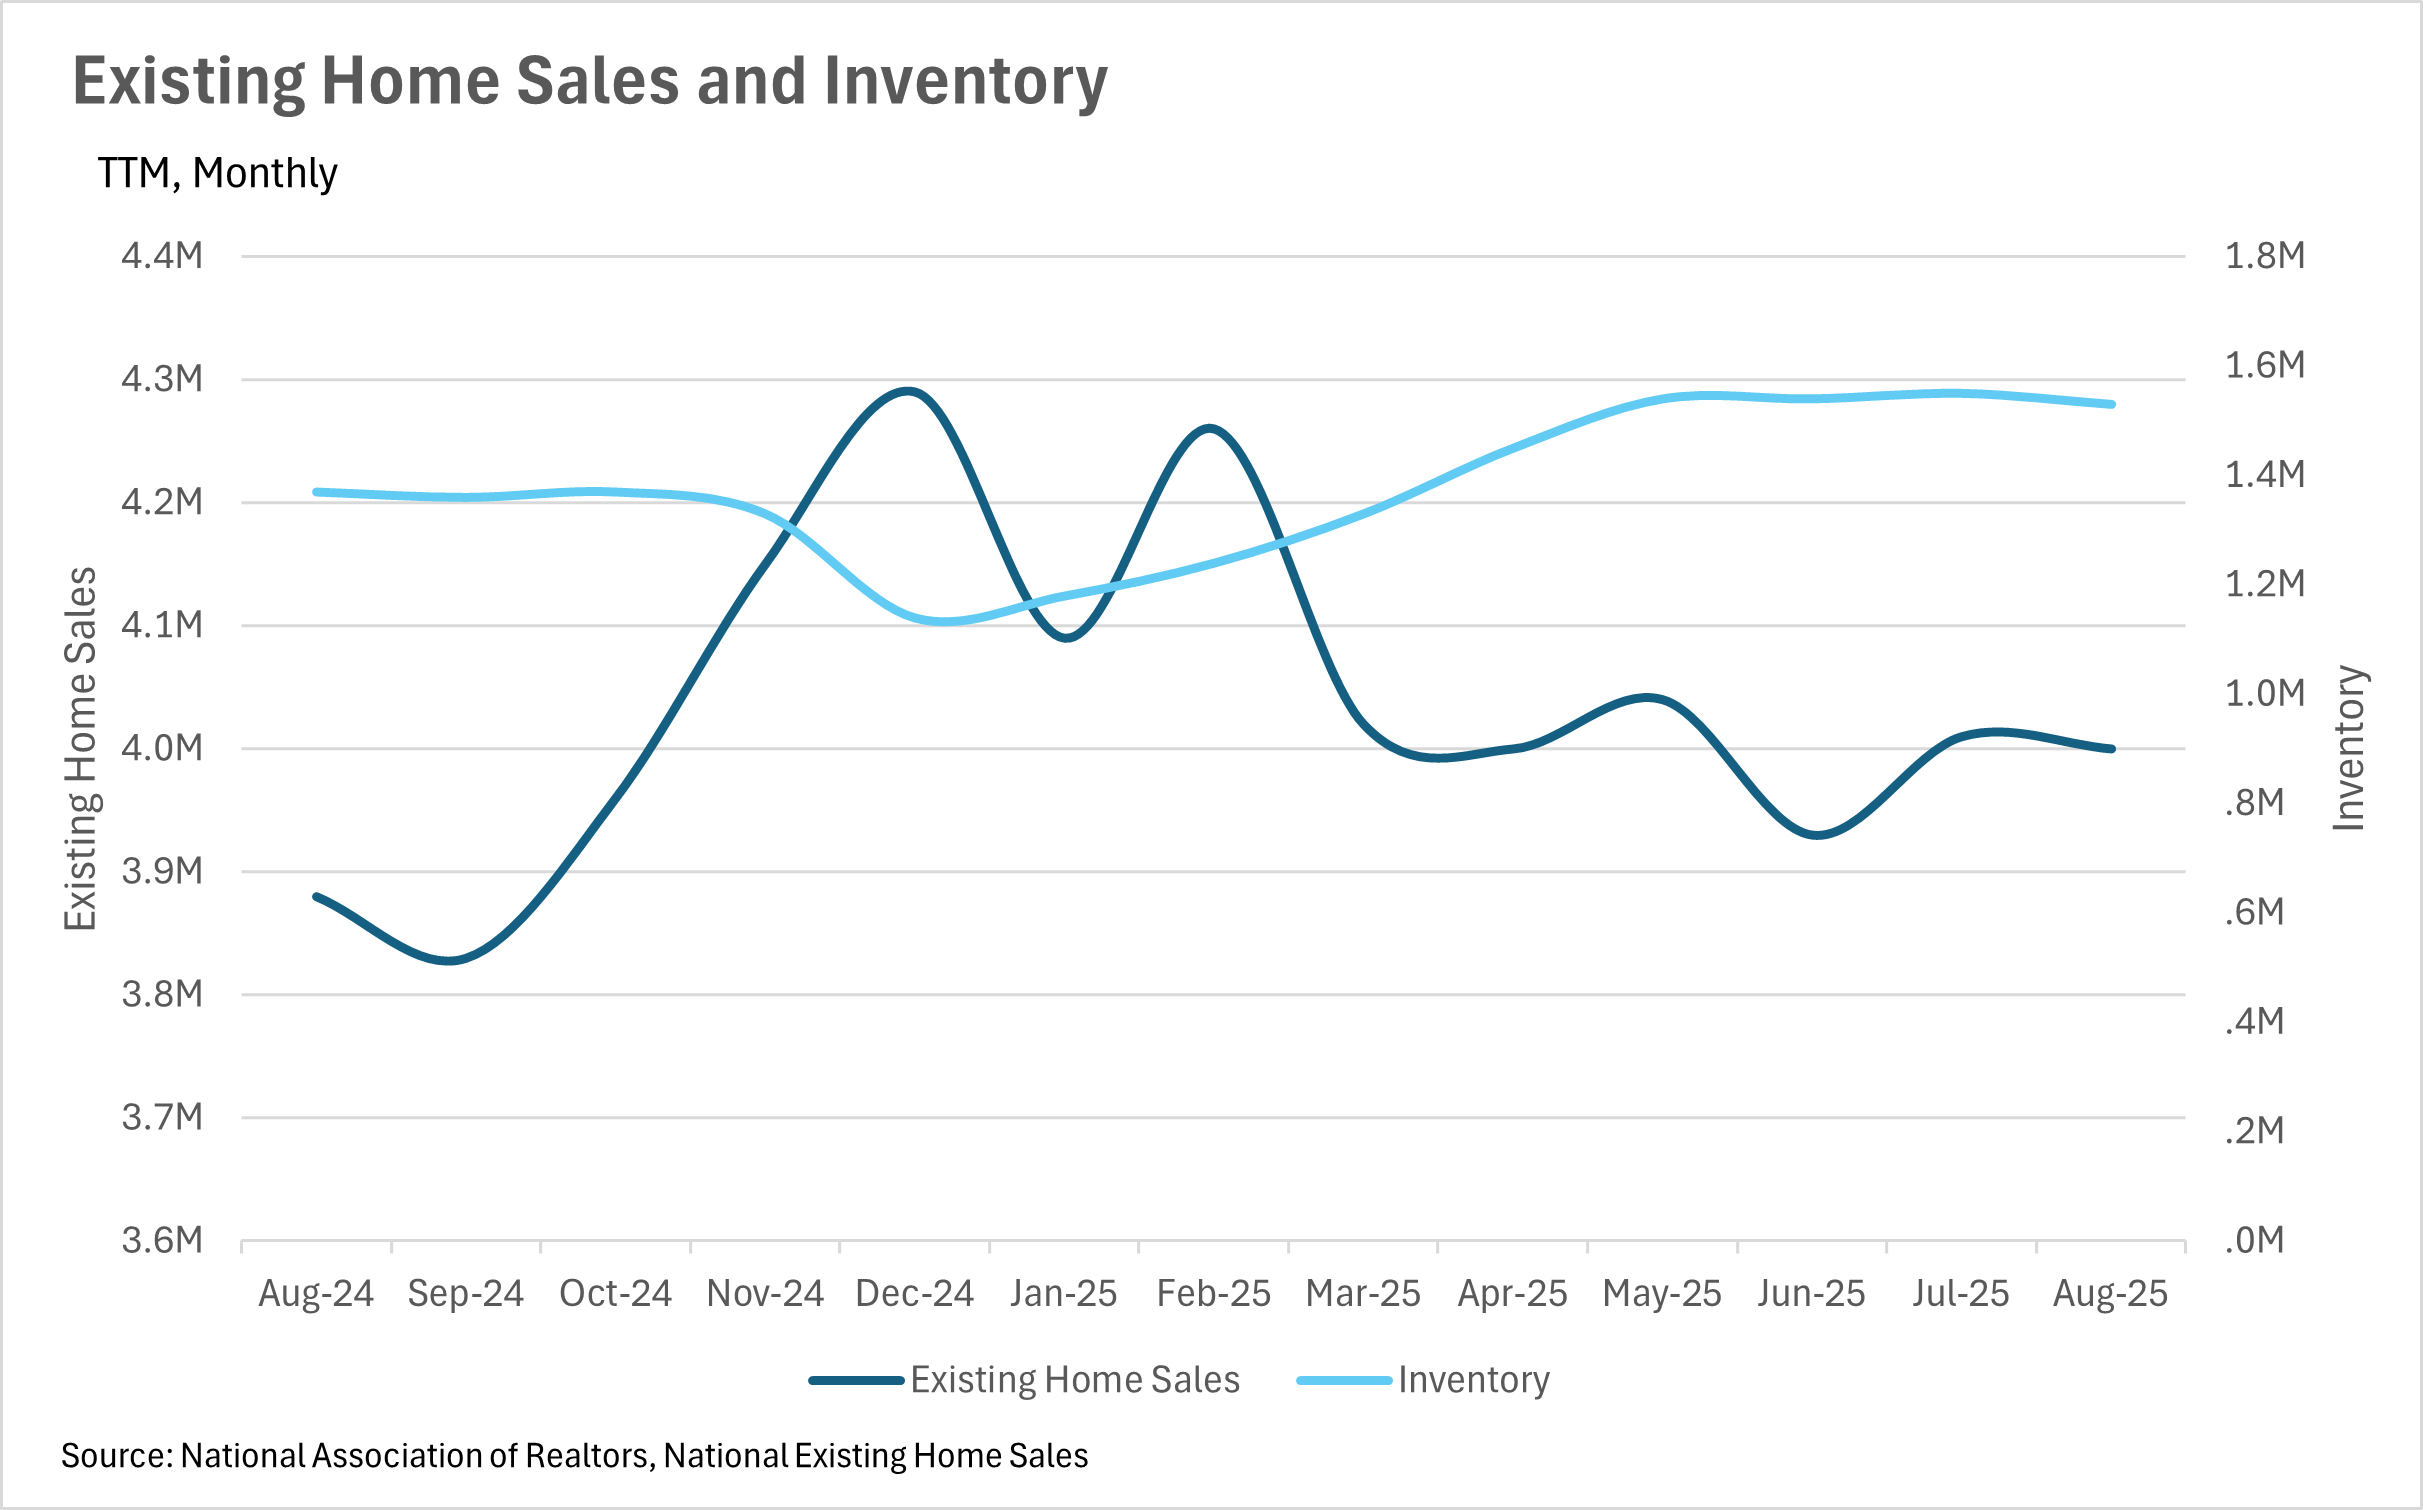
Inventories are still growing at a faster rate than existing home sales.
-
Quick observation about Macroeconomics/The Broader Market
Note: You can find the charts & graphs for the Big Story at the end of the following section.
*National Association of REALTORS® data is released two months behind, so we estimate the most recent month's data when possible and appropriate.
Mortgage rates have begun to decline thanks to the Fed
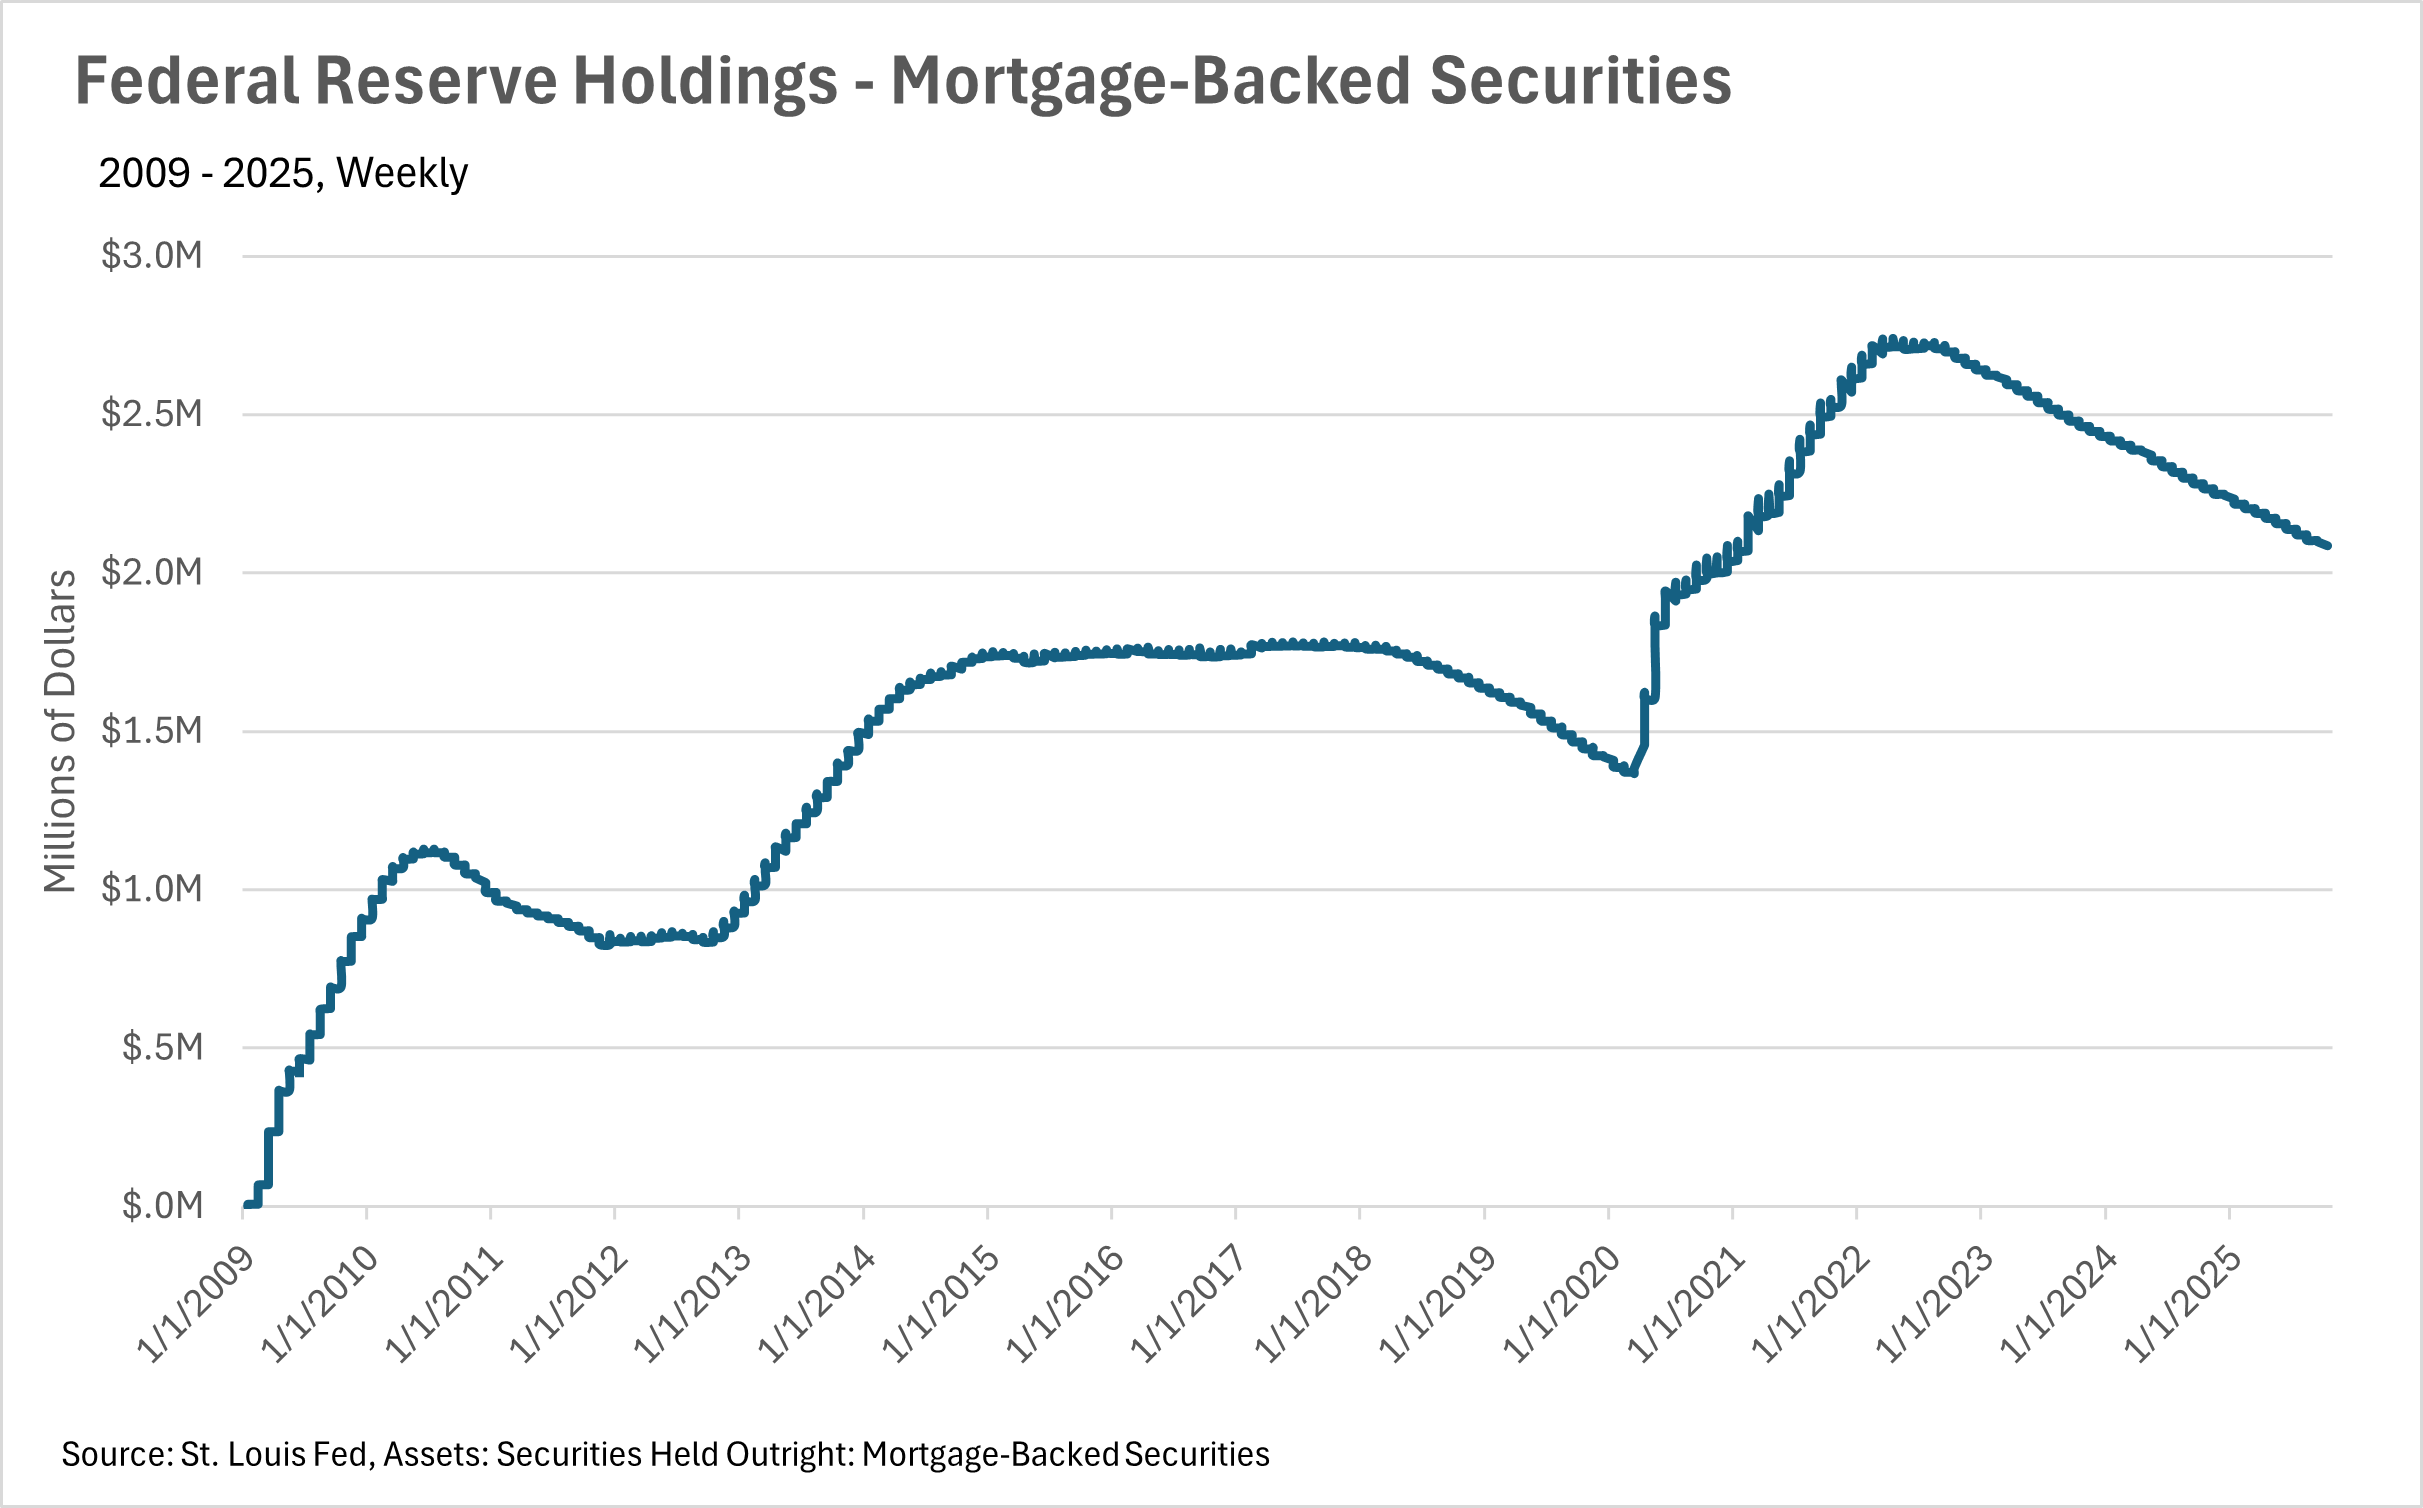
Recently, the Fed came out and announced a quarter-point cut to the federal funds rate, but that was not the most exciting news that they announced. Fed Chairman Jerome Powell announced that we should expect two more quarter-point cuts before the end of the year, signalling that we are in the beginning innings of a Fed cutting cycle. This, of course, is huge news for the housing market. Despite the fact that many markets have retained much of their post-pandemic gains in value, the housing market has been largely stagnant, with inventories building as home buyers decide to sit on the sidelines and wait.
Affordability remains a concern throughout the country
Housing affordability has been a huge problem facing the country ever since the onset of the COVID-19 pandemic. Although many thought that home prices would decrease as interest rates increased, many markets did not see a normalization of home prices. This, of course, has left many prospective home buyers worried about where the market will go as we enter a new rate-cutting cycle. Many fear that lower interest rates may bring a slew of new buyers to the market, pushing home prices up even further, and making home ownership even less attainable for first-time buyers. On the flip side, homeowners stand to benefit in a huge way if declining interest rates lead to a housing frenzy, as they’ll accumulate significant equity in a very small period of time, just like what we saw throughout 2020-2022.
Inventories continue to build nationwide
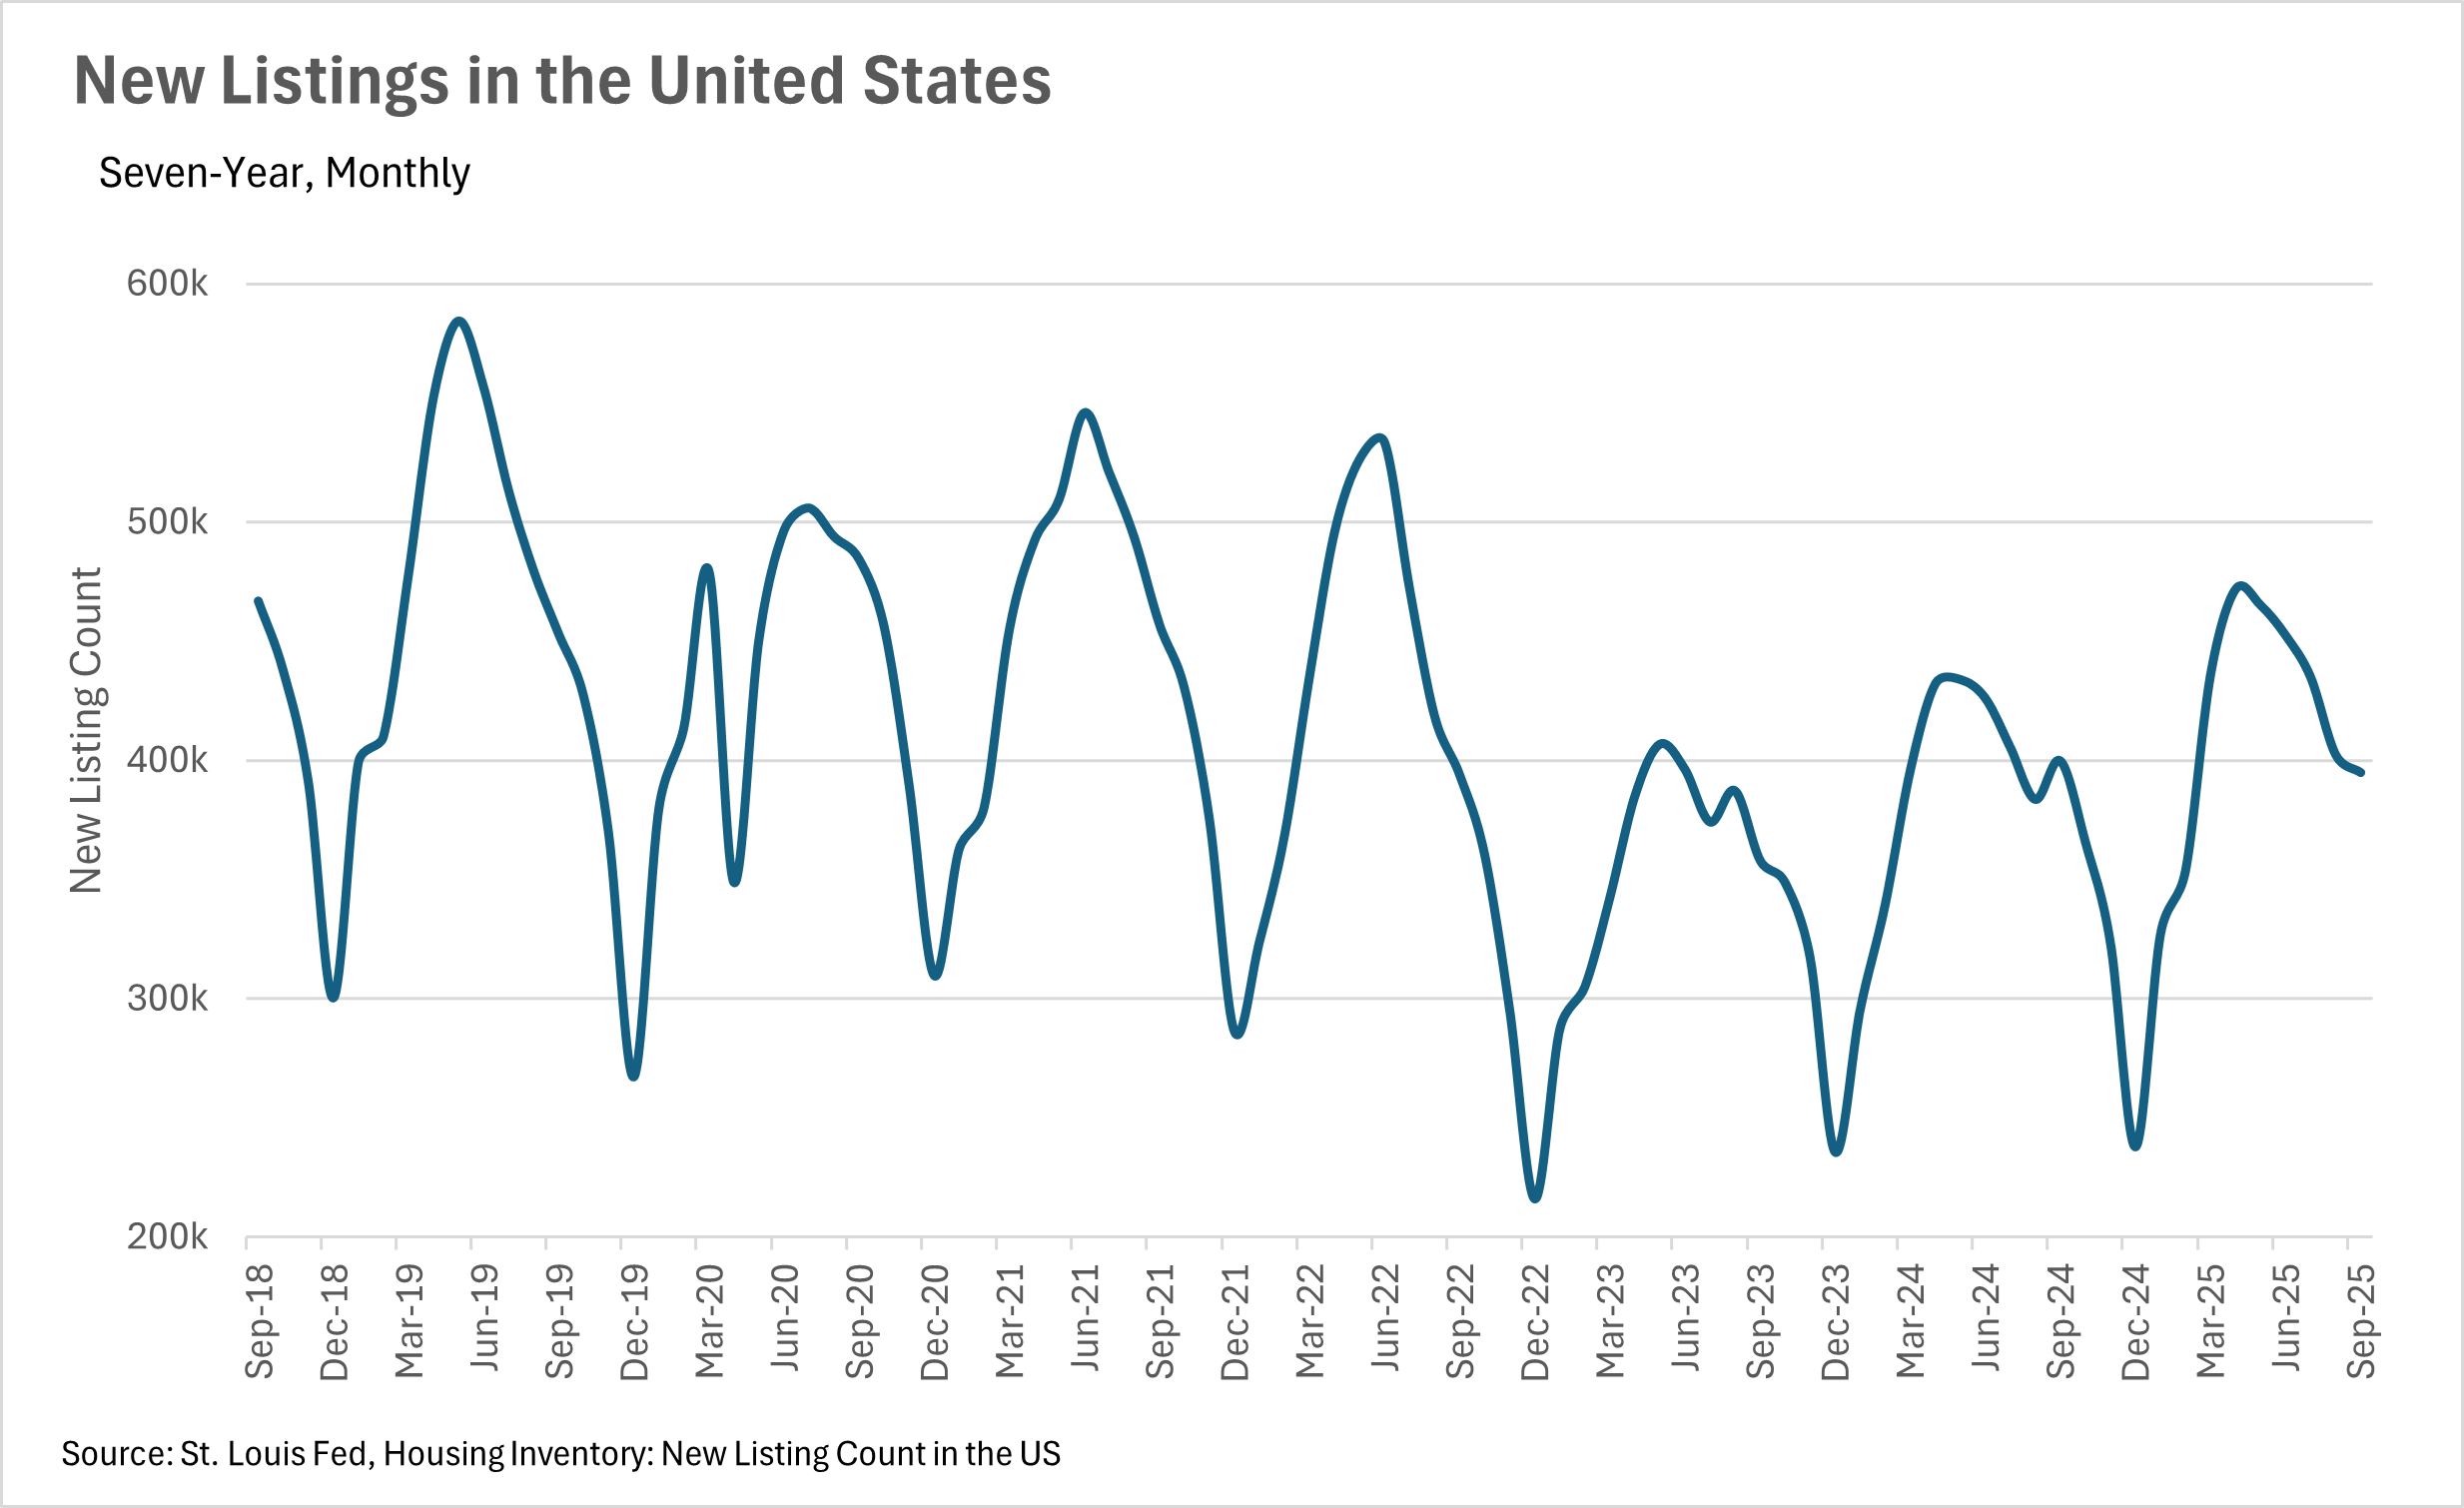
As we mentioned above, the national inventory is quite a bit higher than last year, with 11.68% more homes listed on the market. This really underscores the fact that buyers have decided mainly to throw in the towel and wait for a better chance to purchase a home. When you combine this with the fact that there were 4.88% more new homes hitting the market than this time last year, you have a recipe for growing inventory!
Current market dynamics have created an interesting setup for 2026
As we move into the seasonally slow months, the market environment that we’re in is setting up for what could be a very interesting 2026. Inventories are still growing (for now), and interest rates are falling, which could put us in a very interesting position when the spring frenzy begins next year. It’ll be important to keep a keen eye on both the market and broader macroeconomic conditions throughout the fall and winter, so that you and your clients are ready for whatever spring has to throw at you.
All of this is just what we’re seeing at a national level, though. To get a better idea of what’s going on in your local market, be sure to check out your local lowdown below:
Big Story Data
The Local Lowdown
Quick Take:
-
Median sale prices experienced a renewed year-over-year decline with a 1.07% decrease in August 2025, marking the third month of negative growth this year.
-
Inventory levels show meaningful seasonal retreat with a 7.24% month-over-month decline in September, though still maintaining a 26.59% year-over-year increase.
-
The median listing is now spending 32.5 days on the market, representing a dramatic 47.73% increase compared to the same time last year.
Note: You can find the charts/graphs for the Local Lowdown at the end of this section.
Orange County Prices Return to Negative Territory
Orange County's housing market has returned to year-over-year price declines, with August 2025 seeing the median single-family home selling for $1,385,000, representing a 1.07% decrease compared to August 2024's $1,400,000. This marks the third month of negative year-over-year growth in 2025, following declines in April and May. The median price also showed continued month-over-month weakness, declining 1.07% from July's $1,400,000. The persistent downward pressure on pricing, despite the traditionally active summer selling season, suggests that the abundant inventory and extended selling times are finally translating into meaningful price adjustments as sellers recalibrate their expectations to match current market realities.
Inventory Shows Seasonal Normalization with Meaningful Decline
After months of relentless inventory growth, Orange County's housing market is showing clear signs of seasonal normalization. The latest data for September 2025 shows 4,561 single-family homes on the market, representing a substantial 7.24% month-over-month decline from August's 4,917 homes. While the market still maintains a significant 26.59% year-over-year increase compared to September 2024's 3,603 homes, this monthly retreat marks the second consecutive month of declining inventory levels. This seasonal adjustment suggests that typical market patterns are beginning to reassert themselves after the extraordinary inventory buildup seen throughout the spring and summer. However, with nearly 1,000 more homes available than this time last year, buyers continue to enjoy significantly more options than in previous years.
Market Pace Reaches New Lows as Selling Times Extend Further
The trend toward dramatically longer selling times has reached a new milestone, with properties now taking significantly longer to sell than at any point in the past year. The median single-family home in Orange County now sits on the market for 32.5 days before selling, representing a substantial 47.73% increase from August 2024's 22 days. This also reflects a significant 16.07% month-over-month increase from July's 28-day average, indicating that selling times continue to extend even as we move into the traditionally slower fall season. This extended timeline has become the defining characteristic of the current market, giving buyers unprecedented leverage to conduct exhaustive property searches, secure financing, and negotiate favorable terms without the pressure of competing offers that characterized the market in previous years.
Orange County Maintains Buyers' Market Status Despite Inventory Decline
When determining whether a market is a buyers' market or a sellers' market, we look to the Months of Supply Inventory (MSI) metric. The state of California has historically averaged around three months of MSI, so any area with at or around three months of MSI is considered a balanced market. Any market that has lower than three months of MSI is considered a sellers' market, whereas markets with more than three months of MSI are considered buyers' markets.
With 3.2 months of supply inventory in August 2025, Orange County continues to operate as a buyers' market, though showing slight moderation from earlier summer peaks. This represents a 3.03% month-over-month decrease from July's 3.3 months but still maintains a solid 18.52% year-over-year increase from August 2024's 2.7 months of supply. Despite the recent inventory decline, the market remains above the balanced threshold, providing buyers with continued negotiating advantages. Sellers must recognize that while inventory levels are beginning to normalize seasonally, the fundamental market dynamics still favor buyers, requiring realistic pricing strategies and patience to achieve successful transactions in this environment.